Blog
Contractor Inventory Liquidation Process for Lenders and Asset Managers

The fastest, lowest-risk path to liquidity for contractor-held equipment and materials is a portfolio-based liquidation managed by an experienced asset-recovery partner, run in parallel with title and lien clearance. Idle equipment generates carrying costs through storage, maintenance, and insurance every day it sits unsold, and clean documentation, not auction hype, is what actually shortens the sale cycle. If you manage this decision, start your inventory and title review today, before you choose a sale channel.
Key Takeaways
A portfolio-based liquidation run in parallel with title and lien clearance converts idle contractor inventory into cash faster and with less legal exposure than piecemeal individual sales.
| Point | Details |
|---|---|
| Start inventory and title work together | Run lien searches and condition documentation from day one, not after a buyer appears. |
| Match channel to asset type | Route specialty units to negotiated sale and bulk fleets to portfolio or auction sale. |
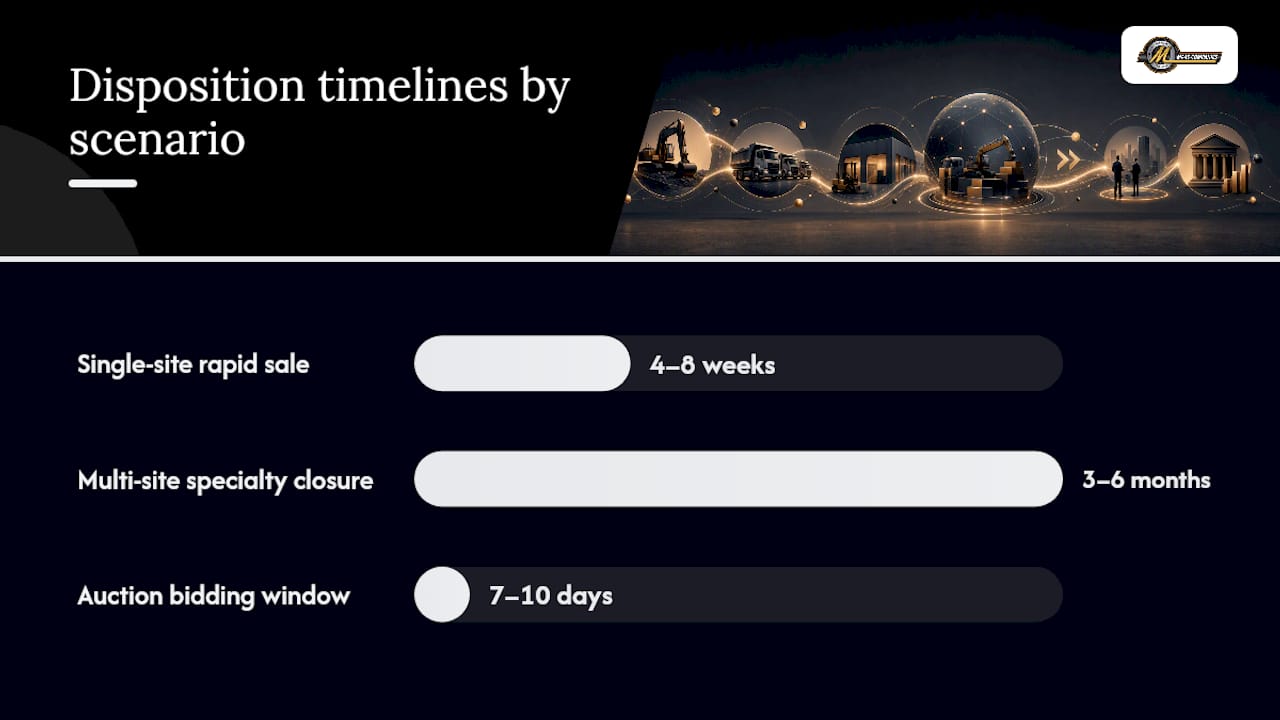
| Expect 4 to 8 weeks for rapid single-site deals | Larger multi-site or lender-ordered closures often run 3 to 6 months. |
| Vet fee models before engaging | Commission structures commonly run 10% to 30% and directly shape net recovery. |
| Use a specialist recovery partner | Maascompanies coordinates inventory, valuation, logistics, title clearance, and settlement as one process. |
Table of Contents
- What Is the Contractor Inventory Liquidation Process?
- How Does the Contractor Inventory Liquidation Process Work Step by Step?
- What Legal and Title Issues Must Be Cleared Before a Sale?
- Should You Sell Assets Individually or as a Portfolio?
- How Do You Coordinate Logistics Without Disrupting Active Jobsites?
- How Do You Vet and Choose a Liquidation Partner?
- What Recovery and Timeline Can You Realistically Expect?
- What Do Asset-Recovery Teams Wish Contractors Knew Earlier?
- How Maascompanies Supports the Contractor Inventory Liquidation Process
- Sources
What Is the Contractor Inventory Liquidation Process?
The contractor inventory liquidation process is the structured conversion of contractor-owned equipment, surplus materials, and jobsite assets into cash through inventory, valuation, marketing, and sale, coordinated with legal clearance and settlement. Choosing the right approach depends on what you’re optimizing for.
For speed and legal certainty: use a portfolio sale run by a specialist recovery firm. To maximize price on high-demand machines: pair that with targeted individual sales for standout units. The rule of thumb: the more units and sites involved, the more a coordinated portfolio approach outperforms piecemeal listings on both timeline and net recovery.
Before selecting a channel, rank your priorities:
- Speed — how quickly capital needs to hit the balance sheet
- Legal certainty — clean title, released liens, no clawback exposure
- Operational continuity — keeping active jobsites running during disposition
- Net recovery — proceeds after fees, logistics, and carrying costs
How Does the Contractor Inventory Liquidation Process Work Step by Step?
The process runs in five phases, and the phases overlap rather than proceed strictly in sequence.
- Inventory and condition reporting. Document every asset by make, model, serial number, hours of use, service records, and photographs. A structured inventory built on these fields is what buyers use to bid with confidence instead of discounting for uncertainty.
- Priority triage. Sort assets into four buckets: critical to ongoing operations, saleable at market with broad buyer demand, specialty items with a narrow buyer pool, and scrap or consumables with minimal individual value.
- Valuation. Run quick appraisals against replacement cost and recent market comps for each bucket. Set target prices and reserve levels that reflect fair market value versus what you’d realistically net in a forced or accelerated sale.
- Channel selection. Route specialty units to direct negotiated sale, route bulk and mixed fleets to portfolio or auction sale, and map an expected timeline for each channel before you commit.
- Documentation and clearance, run in parallel. Title and lien clearance should start the same week as inventory, not after a buyer is found. Waiting until offers arrive to discover an unreleased lien is the single most common cause of delayed closings.
A compact example: a rapid disposition of a single-site fleet can close in 4 to 8 weeks once inventory and title work are complete. A multi-site or lender-ordered closure involving specialty equipment more often runs 3 to 6 months, largely because industrial auction processes involve cataloguing, a defined bidding window of roughly 7 to 10 days, and a post-sale removal window that has to be scheduled around active operations.
Cross-functional coordination determines whether that timeline holds. Operations needs to sign off on which units can leave and when. Finance needs allocation decisions locked before closing, since the IRS treats each asset sale separately for tax purposes and inconsistent allocations between buyer and seller invite scrutiny. Legal needs lien searches complete before marketing begins. Site safety needs a removal sequence that doesn’t strand an active crew without equipment mid-project.
Pro Tip: Photograph accessories and attachments separately from the base unit. Selling buckets, forks, and hydraulic attachments as line items instead of bundling them into the machine price frequently adds recovery that a single lump-sum listing leaves on the table.
What Legal and Title Issues Must Be Cleared Before a Sale?
Buyers pay more, faster, when title is demonstrably clean. Unresolved liens, unreleased UCC filings, or ambiguous ownership create friction that shows up as lower offers, longer due diligence, or a walked deal.
Before listing anything, run through this checklist:
- Proof of ownership for every asset, matched to serial numbers
- UCC lien searches against the contractor entity and any parent company
- Lien releases obtained in writing, not verbally confirmed
- Lease or landlord encumbrances reviewed for jobsite-attached equipment
- Equipment-specific permits, registrations, or titles verified as transferable
Clearing lien and title issues before marketing isn’t paperwork for its own sake. It’s what lets a buyer make a same-week offer instead of tying up capital in escrow while their counsel investigates.
Coordinate with finance early on allocation across asset classes, since tax outcomes shift based on how sale proceeds are allocated between equipment, inventory, and real property. If the disposition happens close to a restructuring or insolvency event, involve counsel on lookback and fraudulent-transfer exposure under state adaptations of the Uniform Voidable Transactions Act, particularly when a sale happens below apparent market value.
Pro Tip: Start UCC searches the same day you begin inventory, not after you have a buyer. A lien discovered mid-negotiation is what kills deals that were otherwise ready to close.
Should You Sell Assets Individually or as a Portfolio?
The right pricing strategy depends on what you’re solving for: fair market value over time, orderly liquidation value under a moderate deadline, or forced-sale value when the clock is the binding constraint.
| Approach | Speed | Price outcome | Certainty |
|---|---|---|---|
| Individual sale | Slow | Highest ceiling on specialty units | Low, buyer-dependent |
| Portfolio sale | Fast | Strong aggregate recovery | High |
| Auction | Moderate | Market-driven, variable | Moderate |
| Negotiated direct sale | Fast | Predictable, negotiated | High |
Portfolio sales through an experienced partner close faster than piecemeal individual listings because they appeal to buyers seeking bulk inventory for resale or rental fleets in one transaction. Auctions add competitive tension and transparency but introduce price uncertainty on any given lot; negotiated sales trade some upside for a locked number, which is usually the better fit for specialty machines with a thin buyer pool.
Set reserves that reflect your actual timeline pressure, not your ideal outcome. A common mistake is setting reserve prices at fair-market comps while operating under a forced-sale deadline. That mismatch creates unsold inventory that ages, and aging inventory becomes a second liquidation project.
- Mix channels deliberately: direct sale for specialty units, portfolio or auction for bulk fleets
- Set separate reserve logic for each bucket rather than one blanket target across the whole inventory
How Do You Coordinate Logistics Without Disrupting Active Jobsites?
Removal has to be staged, not simultaneous. Build a schedule that pulls units in phases aligned to project milestones, moving non-critical equipment first and holding critical assets until their operational role ends.
Resolve these logistics items before the first unit moves:
- Weight and dimensions for rigging and transport planning
- Site access constraints, including crane clearance and load-bearing paths
- Disconnection sequencing for anything wired, plumbed, or hydraulically integrated
- Hazardous materials handling for fuel, coolant, or contaminated components
- Insurance transfer points, so coverage doesn’t lapse between disconnection and buyer pickup
Site managers and the liquidation team need a shared protocol, not a one-time handoff. That means a named point of contact on each side, a phased release calendar, and a documented sign-off at each removal stage. On electrified equipment, coordinating with qualified industrial electrical contractors for safe disconnection avoids both safety incidents and damage claims that erode net recovery.
A phased removal plan tied to project milestones is the difference between liquidation running alongside operations and liquidation stopping them.
Pro Tip: Assign a single site liaison for the entire removal window. Rotating contacts between the liquidation team and site staff is a frequent, avoidable source of scheduling errors and missed access windows.
How Do You Vet and Choose a Liquidation Partner?
Vet partners on capability, not just fee percentage. A partner needs a genuine national buyer network, in-house or coordinated rigging and logistics, title-clearance support, and a documented escrow and settlement process, not a promise to “figure it out” once a buyer appears.
Ask direct questions in the interview: What’s your realistic timeline for a portfolio this size? Can you show a comparable case with actual net-recovery figures? What is your fee structure, and is it commission-based, fixed-fee, or buyer-premium? Commission structures on professional liquidations commonly run between roughly 10% and 30% depending on asset type, volume, and scope of service, and that spread has a direct effect on your net proceeds.
Watch for these red flags:
- Fee structures the partner won’t put in writing before engagement
- A buyer network limited to one region or one asset category
- No documented process for lien and title clearance
- No track record coordinating removal across multiple sites simultaneously
Pro Tip: Ask for a sample settlement statement from a past deal, not just a summary. How proceeds were allocated and reported tells you more about a partner’s rigor than any pitch deck.
What Recovery and Timeline Can You Realistically Expect?
Consider a mid-size contractor exiting three sites with a 40-unit fleet and surplus building materials. Specialty attachments and one crane went to direct negotiated sale. The remaining fleet and materials moved as a portfolio sale with phased removal scheduled around two active projects.
The full disposition closed in roughly six weeks, consistent with the 4 to 6 week window typical of smaller structured dispositions. Title clearance ran in parallel with marketing rather than after it, which is what kept the timeline intact. For lenders facing a similar multi-site exposure, the practical takeaway is to start inventory and lien work the day the liquidation decision is made, not the day a buyer shows interest.
What Do Asset-Recovery Teams Wish Contractors Knew Earlier?
The recurring mistake we see is title clearance treated as a formality instead of a parallel workstream. It gets started only after a buyer is lined up, which stalls closings for weeks. The other frequent gap is thin service documentation on equipment that’s otherwise in strong condition, which forces buyers to price in uncertainty.
A specialist partner absorbs both problems early, which is what actually protects your timeline.
How Maascompanies Supports the Contractor Inventory Liquidation Process
Maascompanies runs the full arc of a contractor liquidation: inventory and condition documentation, valuation, marketing to a national buyer base, logistics and phased removal, title and lien clearance, and final settlement reporting. For lenders and asset managers, that end-to-end coordination matters more than any single auction event, because engaging a professional partner early preserves capital and accelerates recovery across multi-site portfolios, especially in court-ordered or lender-ordered dispositions where documentation has to withstand scrutiny.
Maascompanies has handled court-ordered, lender-ordered, and government foreclosure liquidations across manufacturing, energy, agriculture, and contractor inventory, giving asset managers a partner who has already solved the coordination problems that stall in-house dispositions. Review the full range of services on the Maas services portfolio, or, if you’re ready to move on a specific portfolio, submit details through the equipment brokerage and auction intake page for a rapid assessment and a sample recovery projection.
Sources
For deeper detail, see Maascompanies’ surplus equipment auction guidance, how industrial auctions run from inventory to sale, and legal steps and tax rules for asset liquidation.
- Turning Surplus into Opportunity: Best Practices for Liquidating Construction Assets Quickly | Equipment & Contracting
- How to Liquidate Assets: Legal Steps and Tax Rules - LegalClarity
- How industrial auctions work: From asset inventory to final sale
- Commercial Asset Liquidation for Banks, Lenders & Private Equity
- Industrial Asset Liquidation Guide for Manufacturers | RM Digest
Recommended
- How Industrial Plant Liquidation Maximizes Recovery Value for Lenders | Blog | Insights on Asset Liquidation and Auction Trends
- Top Distressed Asset Liquidation Tools for Institutional Sellers | Blog | Insights on Asset Liquidation and Auction Trends
- Equipment Liquidation Workflow: Maximize Asset Recovery | Blog | Insights on Asset Liquidation and Auction Trends
- Equipment liquidation explained: maximizing asset recovery | Blog | Insights on Asset Liquidation and Auction Trends