Blog
Depreciation Recapture on Equipment Sale: What Sellers Owe

Yes, depreciation recapture applies whenever you sell equipment for more than its adjusted basis, and it typically turns a large share of your gain into ordinary income rather than capital gain. Under Section 1245, the recapture amount equals the lesser of your total gain or the cumulative depreciation you claimed (or could have claimed) on the asset. This is not optional and it is not a planning choice you can sidestep after the sale closes.
Before you sign a bill of sale or set a reserve price for an auction, do three things:
- Calculate your adjusted basis (original cost plus improvements, minus all depreciation allowed or allowable).
- Compare adjusted basis to the amount realized to determine total gain, then isolate the recapture portion.
- Set aside cash for the ordinary-income tax hit and prepare to report the sale on Form 4797.
Quick fact: Recapture under Section 1245 is capped at the amount of depreciation you actually took or were entitled to take. You cannot be taxed on more ordinary income than the depreciation deductions you already benefited from.
Key Takeaways
Depreciation recapture converts equipment sale gains into ordinary income up to the amount of depreciation claimed, and calculating it correctly before you set a sale price protects your net proceeds.
| Point | Details |
|---|---|
| Recapture is capped, not open-ended | Ordinary income recognition equals the lesser of total gain or cumulative depreciation claimed on the asset. |
| Calculate basis before pricing | Adjusted basis, amount realized, and total gain must be computed before you set a reserve price or accept an offer. |
| Form 4797 Part III drives reporting | Recapture calculates in Part III, then any remaining gain flows to Part I for Section 1231 netting. |
| Installment sales don’t defer recapture | The full recapture amount is taxed in the year of sale regardless of payment timing under the installment method. |
| Trade-ins are taxable dispositions | A trade-in allowance counts as amount realized on the old asset, triggering recapture the same as a cash sale. |
Table of Contents
- Worked Examples: How Depreciation Recapture on Equipment Sale Is Calculated
- Section 1245 vs Section 1250: Which Recapture Rule Applies to Your Equipment
- How to Calculate Depreciation Recapture Step by Step
- Form 4797 Reporting Mechanics and Year-End Interactions
- Tax Rates and Related Surtaxes That Affect Net Proceeds
- Planning Strategies and Pitfalls in Equipment Dispositions
- Pricing, Sale Method, and Documentation: A Disposition Partner’s View
- Related-Party Sales and Recapture Treatment
- Special Rules for Small Businesses and Equipment Dealers
- Trade-Ins and Replacement Property: How They Change the Calculation
- Depreciation Recapture and Casualty or Theft Losses
- Recordkeeping, the Allowed-or-Allowable Rule, and Partnership Distributions
- What Equipment Sellers Consistently Get Wrong About Recapture
- Sources
Worked Examples: How Depreciation Recapture on Equipment Sale Is Calculated
Numbers settle arguments faster than definitions do. Here are two scenarios that cover the situations most equipment sellers actually face: a sale below original cost, and a sale above it.
Example A: Sale price below original cost
A manufacturing company bought a CNC machining center for $200,000. Over five years, it claimed $150,000 in depreciation, leaving an adjusted basis of $50,000. The company sells the machine for $120,000.
- Adjusted basis: $200,000 cost minus $150,000 depreciation equals $50,000.
- Amount realized: $120,000 (sale price, assuming no selling costs for simplicity).
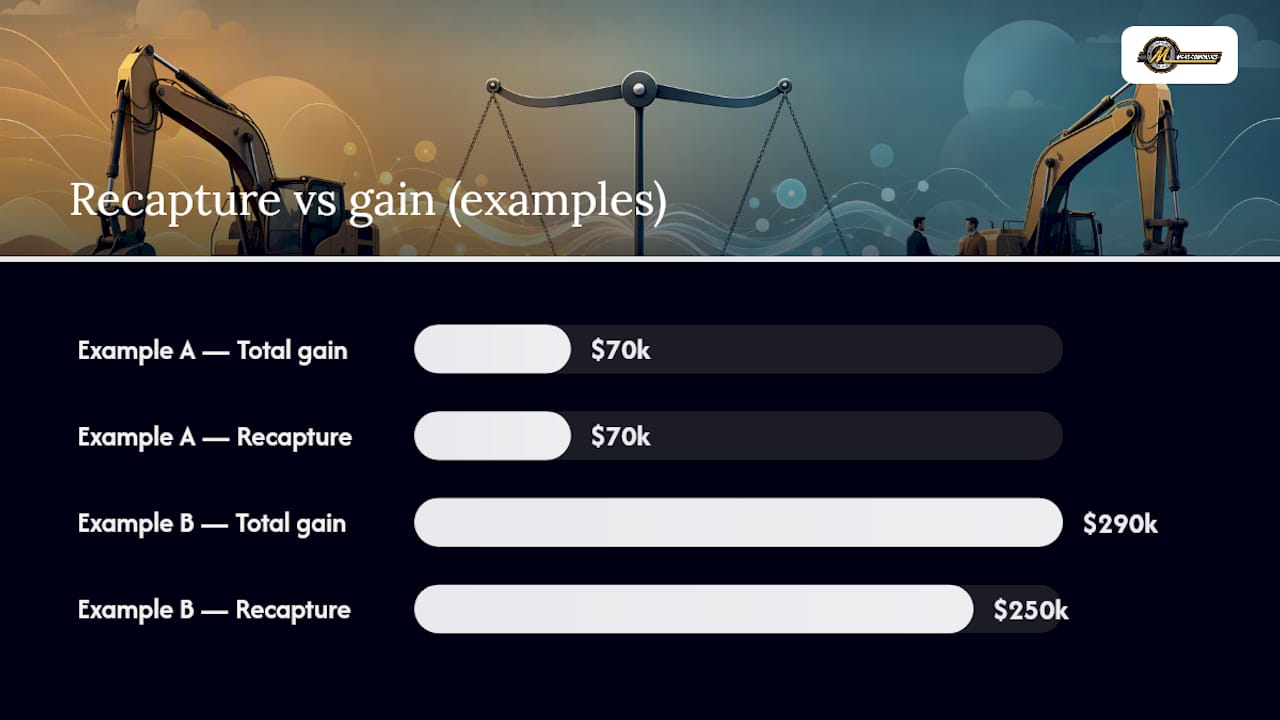
- Total gain: $120,000 minus $50,000 equals $70,000.
- Recapture amount: the lesser of total gain ($70,000) or total depreciation claimed ($150,000). Since $70,000 is smaller, the entire $70,000 gain is recaptured as ordinary income.
- Section 1231 gain remaining: zero. Nothing is left over for capital gain treatment.
Because the sale price never exceeded the original purchase price, every dollar of gain traces back to depreciation the company already deducted. This is the most common outcome for mid-life industrial equipment sold in a normal market and it surprises sellers who assumed a sale below cost would somehow escape ordinary-income treatment.
Example B: Sale price above original cost
A logistics firm bought a forklift fleet for $300,000. It claimed $250,000 in depreciation, leaving an adjusted basis of $50,000. A tight used-equipment market lets the firm sell the fleet for $340,000.
- Adjusted basis: $300,000 minus $250,000 equals $50,000.
- Amount realized: $340,000.
- Total gain: $340,000 minus $50,000 equals $290,000.
- Recapture amount: the lesser of total gain ($290,000) or total depreciation claimed ($250,000). Here, depreciation is smaller, so $250,000 is recaptured as ordinary income.
- Section 1231 gain remaining: $290,000 minus $250,000 equals $40,000, taxed under Section 1231 rules, generally as long-term capital gain if the five-year lookback does not intervene.
The split matters because ordinary income and Section 1231 gain land in different places on your return and carry different tax rates. Sellers who only track “profit over cost” often miscalculate their tax exposure, because the accounting question is never how much you made over what you paid. It’s how much of the sale price exceeds your adjusted basis, and how much of that traces to depreciation you already deducted, per Publication 544.
Section 1245 vs Section 1250: Which Recapture Rule Applies to Your Equipment
Most equipment sellers deal with one recapture regime, and knowing which one applies up front saves a lot of confusion later.
Section 1245 property covers tangible personal property used in a trade or business, including manufacturing machinery, vehicles, forklifts, computers, and most equipment sold through an industrial liquidation. Under 26 U.S.C. §1245, gain on disposition is treated as ordinary income up to the full amount of depreciation claimed. There is no reduced rate, no capital gain preference on the recaptured portion, full stop.
Section 1250 property covers depreciable real property, buildings and structural components. If a sale involves real estate alongside equipment, such as a plant closure that includes both the building and the machinery inside it, the building’s gain may fall under “unrecaptured Section 1250 gain,” capped at a 25% federal rate rather than taxed at ordinary rates. This distinction is why plant liquidations often require separate basis tracking for real property and personal property. Blending the two invites reporting errors.
A few narrower rules deserve a mention, since they surface often enough in equipment sales to warrant attention:
- Section 179 recapture: if you expensed equipment under Section 179 and then dropped business use below 50% before the recovery period ended, you must recapture the excess deduction as ordinary income, even without a sale.
- Listed property rules: equipment such as vehicles and certain computers face additional recordkeeping and recapture triggers under Publication 946 if business use falls below the threshold that qualified them for accelerated depreciation.
- Sections 1252, 1254, and 1255: these apply to farmland, oil and gas property, and cost-sharing payments respectively. They rarely touch standard industrial equipment sales, but appear in agricultural liquidations.
Pro Tip: If your disposal includes a mix of real property and equipment, get separate appraisals and separate depreciation schedules for each category before you negotiate a price. A single lump-sum sale price without asset-level allocation is one of the most common triggers for IRS scrutiny and buyer/seller disputes over basis.
How to Calculate Depreciation Recapture Step by Step
The math itself is not complicated. What trips people up is missing an input or misreading which line on Form 4797 a number belongs on. Follow this sequence and you will land on the correct figure every time.
Step 1: Gather your inputs.
- Original purchase price, including delivery and installation costs that were capitalized.
- Any capital improvements made after purchase (major overhauls, upgrades, retrofits).
- Total accumulated depreciation claimed, including regular depreciation, Section 179 expensing, and bonus depreciation.
- Selling price and any selling costs (broker commissions, auction fees, transport to buyer).
- Business-use percentage, if the equipment was ever used partly for personal purposes.
Step 2: Apply the formulas.
- Adjusted basis = original cost + capital improvements − total depreciation allowed or allowable.
- Amount realized = sale price − selling costs.
- Total gain = amount realized − adjusted basis.
- Recapture amount = the lesser of total gain or total depreciation claimed on the asset.
- Remaining Section 1231 gain (if any) = total gain − recapture amount.
Step 3: Place the numbers on Form 4797.
Depreciation recapture on personal property gets reported in Part III of Form 4797, which walks through the recomputation of gain and isolates the ordinary-income portion under Section 1245. The instructions for Form 4797 detail exactly which lines capture cost, depreciation, and recomputed basis, and they are worth reading line by line rather than skimming, since a misplaced figure in Part III flows incorrectly into your total ordinary income.
Once Part III calculates the recapture amount, that ordinary income transfers to Form 1040 as part of your total income for the year. Any gain left over after recapture flows to Part I of Form 4797, where it nets against other Section 1231 gains and losses for the year before determining whether the remainder gets long-term capital gain treatment.
A quick checklist before you file:
- Confirm which depreciation method and recovery period applied to the asset, since this affects total depreciation claimed.
- Verify whether Section 179 or bonus depreciation was used, since both count fully toward the recapture calculation.
- Match your calculated recapture amount to the specific line in Part III that corresponds to the property type.
- Keep the original purchase invoice, depreciation schedule, and sale agreement together as your audit file.
Business owners selling multiple pieces of equipment in one transaction, common in plant closures and restructurings, need to run this calculation separately for each asset or asset group with distinct basis. Lumping everything into one blended number tends to produce a recapture figure that is either overstated or understated, and either error creates problems with the IRS or with the buyer’s own tax reporting.
Form 4797 Reporting Mechanics and Year-End Interactions
Part III of Form 4797 exists specifically to isolate the ordinary-income recapture piece before anything touches capital gain treatment. The form walks you through recomputed basis, subtracts it from the amount realized, and caps the recapture at total depreciation claimed. Whatever survives that calculation moves to Part I, where it joins your other Section 1231 transactions for the year.
That transfer to Part I matters because of the five-year lookback rule. If you had net Section 1231 losses in any of the five preceding tax years, and those losses were deducted as ordinary losses, the IRS requires you to recharacterize an equivalent amount of this year’s Section 1231 gain as ordinary income. Sellers who had a rough year three years ago and used equipment losses to offset other income sometimes forget that recapture math isn’t finished until they check this lookback. Publication 544 walks through the mechanics, and it’s a step preparers miss more often than any other in the Section 1231 process.
Installment sales add a separate wrinkle. If you finance part of the sale and collect payments over multiple years, depreciation recapture cannot be spread out. The full recapture amount is recognized as ordinary income in the year of sale, regardless of how much cash you actually collected that year. Only the non-recapture portion of the gain, the Section 1231 piece, qualifies for installment deferral under Form 6252, according to guidance tied to Form 4797.
Quick fact: an installment sale does not defer recapture tax. If you sell $400,000 of equipment with $250,000 in recapture and collect only a $100,000 down payment, you still owe ordinary income tax on the full $250,000 in the year of sale.
Reporting checklist for the year of sale:
- Complete Form 4797 Part III to isolate recapture before touching Part I.
- Check the five-year lookback for prior Section 1231 losses that might recharacterize current gain.
- If financing the sale, file Form 6252 for the non-recapture portion only, and report recapture in full on Form 4797.
- Reconcile the Form 4797 total with the gain reported on Schedule D if any capital gain portion survives after recapture and lookback adjustments.
Tax Rates and Related Surtaxes That Affect Net Proceeds
The recapture portion of your gain is taxed at your marginal ordinary income rate, the same bracket that applies to salary or business income. This is the single biggest reason recapture surprises sellers: a gain they expected to see taxed at a 15% or 20% long-term capital gains rate instead lands at a rate as high as 37% for high-income filers.
Contrast that with unrecaptured Section 1250 gain, which applies to real property rather than equipment and carries a capped rate of 25%. If your disposal includes both a building and machinery, the equipment gain and the building gain can be taxed at different effective rates on the same closing statement. That is worth flagging to whoever is negotiating the deal on your behalf, since buyers rarely think about seller tax consequences when structuring an offer.
The Net Investment Income Tax adds another layer for higher-income sellers. Once modified adjusted gross income crosses the applicable threshold, an additional 3.8% surtax applies to certain investment income categories, which can include the capital gain portion of an equipment sale in some structures, per Fieldvest’s guide to qualified investment income. NIIT generally does not apply to the ordinary-income recapture portion itself, but it can raise the effective rate on whatever capital gain remains after recapture is carved out.
State taxes vary widely and deserve a dedicated conversation with your accountant. Some states tax capital gains at the same rate as ordinary income, eliminating the federal rate differential entirely. Others offer partial exclusions for business asset sales. A few have no income tax at all. None of this changes the federal recapture calculation, but it changes how much of your net proceeds you actually keep, which is the number that matters when you are deciding whether a sale price makes sense.
- Ordinary recapture: taxed at your marginal federal rate, no reduced rate available.
- Section 1250 real property gain: capped at 25% federal rate when applicable.
- NIIT: an additional 3.8% on qualifying investment income above MAGI thresholds.
- State tax treatment: varies by state; confirm before finalizing sale price expectations.
Planning Strategies and Pitfalls in Equipment Dispositions
Recapture cannot be eliminated, but timing and structure change when and how much you pay. A handful of strategies come up repeatedly among sellers managing large equipment dispositions.
1031 exchanges historically deferred gain on like-kind property, but the Tax Cuts and Jobs Act narrowed this benefit to real property only, starting in 2018. Equipment and other personal property no longer qualify for 1031 deferral, which closes off a strategy many longtime business owners assume still applies. If your disposal includes real estate alongside equipment, the real property portion may still qualify. The equipment will not.
Installment sales can smooth out cash flow, but as covered earlier, they do nothing to defer the recapture tax itself. Sellers sometimes structure a deal expecting to spread the tax hit alongside the payments, only to find the full ordinary-income bill due in year one regardless of what the buyer has actually paid.
Timing around the five-year lookback is a legitimate tactical lever. If you know a large equipment sale is coming and you have flexibility on timing, understanding your Section 1231 history for the prior five years can help you anticipate whether this year’s gain will face recharacterization.
Common pitfalls worth naming directly:
- Confusing cash received with taxable gain. A seller who nets $150,000 in cash after paying off a loan may still owe recapture tax calculated on the full amount realized, not the net cash received.
- Poor asset allocation in bulk sales. Selling a plant’s contents as one lump sum without itemized allocation invites disputes with the buyer and increases audit risk.
- Incomplete depreciation schedules. Missing records force reconstruction under the allowed-or-allowable rule, and reconstructed numbers rarely favor the seller.
- Section 179 and bonus depreciation traps. Equipment expensed heavily in year one and sold or converted to personal use soon after creates a larger recapture exposure than sellers expect, since the full deducted amount counts toward the recapture cap.
Pro Tip: Run your recapture calculation before you set a reserve price or opening bid, not after the sale closes. Knowing your after-tax proceeds in advance changes what price actually makes the sale worthwhile.
Pricing, Sale Method, and Documentation: A Disposition Partner’s View
Recapture math is not just an accounting exercise that happens after the sale. It shapes the decision itself, from reserve price to sale method. A company weighing an auction against a negotiated sale needs to know, before it commits, how much of the proceeds will go to ordinary income tax rather than sitting in the bank as usable capital.
At Maas Companies, asset-recovery planning starts with the seller’s full financial picture, not just the equipment’s market value. A machine that appears to fetch a strong price at auction may still leave a seller with less usable cash than a slightly lower negotiated sale, once recapture tax and closing costs are factored in. Sellers, lenders, and restructuring advisors managing plant closures or capital recovery mandates need that comparison before, not after, choosing an execution method.
Documentation quality also affects buyer confidence and final price. Clear depreciation schedules and accurate asset descriptions reduce the friction that comes with allocation disputes, particularly in bulk industrial sales involving dozens or hundreds of line items.
A seller who can hand over a clean depreciation schedule, itemized asset list, and documented business-use history closes faster and negotiates from a stronger position than one who arrives with incomplete records and a single lump-sum asking price.
Before engaging a disposition partner, ask these questions directly:
- Does the partner provide documentation support for tax reporting, or only sale execution?
- How does the firm handle asset-level allocation in bulk or plant-wide sales?
- What is the firm’s track record with court-ordered, lender-ordered, or government foreclosure liquidations, where documentation standards are often higher?
- Can the partner coordinate with your CFO or tax advisor to align reserve pricing with after-tax proceeds targets?
Reviewing recent machinery auction strategies and prior negotiated sale outcomes gives sellers a concrete sense of how execution choices play out for comparable asset classes.
Related-Party Sales and Recapture Treatment
Selling equipment to a related party, a subsidiary, a family member’s business, or an entity under common control, does not exempt the transaction from depreciation recapture. The recapture calculation runs exactly the same way: adjusted basis, amount realized, total gain, and recapture capped at cumulative depreciation.
What changes with related-party transactions is the level of scrutiny the IRS applies to the sale price itself. Related-party deals face closer examination of whether the transaction price reflects fair market value, since undervaluing the sale could shift gain recognition and understate recapture, while overvaluing it could create issues for the buying entity’s basis going forward.
Certain related-party transactions also trigger loss disallowance rules, though this matters more when a sale generates a loss than a gain. If equipment is sold to a related party at a loss, the loss is often disallowed entirely rather than merely deferred, which changes the tax math significantly compared to an arm’s-length sale to an unrelated buyer.
Businesses considering an intercompany equipment transfer, common during restructuring or when consolidating operations across affiliated entities, should document the valuation basis independently. An appraisal or market comparison from a disposition specialist establishes a defensible fair market value, which protects both parties if the transaction is later questioned. This documentation matters more in related-party deals than in open-market sales precisely because there is no arm’s-length negotiation to point to as evidence of a fair price.
Special Rules for Small Businesses and Equipment Dealers
Most small and midsize businesses selling equipment they used in operations follow the standard Section 1245 recapture rules outlined throughout this article. There is no blanket exemption for small business size, and no reduced recapture rate simply because the seller is not a large corporation.
Equipment dealers, businesses that hold equipment as inventory for resale rather than as a depreciable business asset, face a different framework entirely. Inventory sales generate ordinary income under standard business income rules, not capital gain or Section 1231 treatment, and depreciation recapture does not apply because inventory is not depreciated in the first place. The distinction between “equipment used in your business” and “equipment held for sale to customers” determines which set of rules governs the transaction, and getting this classification wrong on a tax return creates significant exposure.
Small businesses that used Section 179 expensing heavily in early years, common for growing operations trying to minimize taxable income, face a particular exposure: the full expensed amount counts toward the recapture cap when the equipment is later sold, even though the deduction felt like a one-time break at the time. There is no size-based exception that reduces this exposure. A five-person machine shop and a five-hundred-person manufacturer follow the identical calculation under Publication 946.
Businesses transitioning equipment from business use to personal use, or reducing business-use percentage below 50%, trigger recapture rules even without a formal sale, a detail that catches small business owners off guard more often than large corporations with dedicated tax staff.
Trade-Ins and Replacement Property: How They Change the Calculation
Trading in old equipment toward the purchase of a replacement used to allow gain deferral under prior like-kind exchange rules, but that treatment for personal property ended with the Tax Cuts and Jobs Act. Today, a trade-in of business equipment is treated as a taxable sale of the old asset combined with a purchase of the new one, meaning recapture on the old equipment is calculated and recognized immediately, exactly as if you had sold it for cash.
The tricky part is determining the “amount realized” on the traded-in asset. Dealers typically structure a trade-in allowance that reduces the price of the new equipment, rather than issuing separate cash for the old unit. For tax purposes, that trade-in allowance counts as the amount realized on the disposition of the old equipment, which means you still calculate adjusted basis, total gain, and recapture on that allowance figure, even though no cash changed hands directly for the old asset.
This creates a common blind spot: business owners see a straightforward equipment upgrade, not a taxable event, and fail to report the recapture from the traded-in unit. The dealer’s paperwork rarely breaks out the trade-in as a separate sale with its own basis calculation, so the responsibility falls on the buyer’s tax preparer to extract that figure from the purchase agreement and calculate recapture on the old asset separately.
If your business regularly upgrades equipment through trade-ins, keep the trade-in allowance documented on every purchase agreement and run the recapture calculation on the retired asset each time, using the same adjusted basis and depreciation figures you would use for a standalone cash sale.
Depreciation Recapture and Casualty or Theft Losses
Equipment destroyed by fire, flood, or theft creates a different tax event than a sale, but depreciation still plays a central role in the calculation. When insurance proceeds or other reimbursement exceed the adjusted basis of the destroyed or stolen equipment, the excess can trigger gain recognition, and that gain is subject to the same Section 1245 recapture rules that apply to a voluntary sale.
The mechanics mirror a standard disposition: compare the adjusted basis to the amount realized, which in a casualty context typically means insurance proceeds. If proceeds exceed adjusted basis, you have a gain, and recapture applies up to the lesser of that gain or cumulative depreciation claimed, following the same framework detailed in Publication 544.
Business owners who replace destroyed equipment using insurance proceeds may qualify for involuntary conversion deferral under Section 1033, a distinct provision from the like-kind exchange rules eliminated for personal property. Section 1033 still permits deferral for involuntary conversions, including casualty and theft, if replacement property is acquired within the required time window. Unlike a voluntary trade-in, this deferral option remains available for equipment lost through casualty or theft, making the loss-and-replace scenario meaningfully different from a straightforward equipment upgrade.
Businesses filing casualty loss claims should document both the original depreciation schedule and the insurance settlement calculation, since the IRS will expect the same “allowed or allowable” depreciation figures used in any other disposition.
Recordkeeping, the Allowed-or-Allowable Rule, and Partnership Distributions
The IRS calculates recapture based on depreciation “allowed or allowable,” a phrase that carries real weight. It means that even if you never claimed depreciation you were entitled to, whether from an oversight, poor recordkeeping, or a deliberate choice to skip the deduction, the IRS still reduces your basis and calculates recapture as though you had claimed it, per Treasury regulation §1.1245-2. Skipping depreciation deductions does not protect you from recapture tax. It just means you paid more tax along the way with no offsetting benefit at the time of sale.
This rule makes recordkeeping essential rather than optional. If your depreciation schedules are incomplete or missing, you may need to reconstruct them from purchase invoices, prior tax returns, and asset registers, and any reconstruction should err toward completeness, since the IRS assumes maximum allowable depreciation was taken absent evidence otherwise.
Partnerships and distributions add another layer of complexity. When a partnership distributes Section 1245 property to a partner rather than selling it, recapture generally does not trigger at the moment of distribution, but the recapture potential travels with the asset and applies when the partner or the partnership eventually disposes of it. Partnerships allocating depreciation and gain among partners with different ownership percentages or different entry dates need careful basis tracking at both the partnership and partner level to avoid disputes when the eventual sale occurs.
What Equipment Sellers Consistently Get Wrong About Recapture
The conventional advice on depreciation recapture treats it as a filing detail, something your accountant handles after the sale is done. That framing gets the sequence backward. Recapture should shape the deal before it shapes the tax return.
The research is clear on one point: sellers who confuse cash received with taxable gain consistently miscalculate what a sale is actually worth to them. A machine that nets $150,000 in cash after debt payoff might still generate a $250,000 ordinary-income tax bill, and no amount of good bookkeeping after the fact changes that outcome once the sale has closed.
What deserves more attention than it gets: the connection between sale method and after-tax proceeds. An auction that produces a higher headline price is not automatically the better outcome once recapture, allocation clarity, and closing costs enter the picture. Sellers should model their after-tax number under a couple of different price and method scenarios before choosing a path, using the tax implications outlined here as the starting framework, not an afterthought.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
Every calculation in this article traces back to a handful of authoritative sources worth bookmarking directly:
- Form 4797 (Sales of Business Property) — IRS
- Treas. Reg. §1.1245–2 (CFR) — Recomputed basis and related rules
Recommended
- What Is Equipment Remarketing? A Decision-Maker’s Guide | Blog | Insights on Asset Liquidation and Auction Trends
- Surplus equipment sale guide: maximize asset recovery fast | Blog | Insights on Asset Liquidation and Auction Trends
- How to conduct equipment auctions for maximum asset recovery | Blog | Insights on Asset Liquidation and Auction Trends
- Equipment liquidation explained: maximizing asset recovery | Blog | Insights on Asset Liquidation and Auction Trends