Blog
Environmental Liability Transfer: A Seller’s Playbook

Environmental liability transfer means selling or liquidating industrial assets, real estate, or equipment that carry contamination or regulatory exposure, using contract terms and deal structure to shift responsibility toward the buyer. The immediate legal reality: a purchase agreement can reassign contractual obligations, but it cannot erase a seller’s exposure to government claims under CERCLA §107(e). Getting real risk reduction requires layering several tools together, not just signing an indemnity clause.
Sellers who treat this as a one-document problem get burned. The transactions that actually protect recovery value combine:
- A seller-commissioned Phase I (and, if warranted, Phase II) Environmental Site Assessment
- Indemnification language with defined survival periods, caps, and baskets
- Escrow or milestone holdbacks tied to independent verification
- State voluntary cleanup program (VCP) enrollment where closure is achievable
- Environmental insurance to cover residual or newly discovered conditions
Key Takeaways
Environmental liability transfer works only when contractual indemnities, escrow mechanics, and insurance operate together, since none of the three alone can eliminate statutory exposure under CERCLA.
| Point | Details |
|---|---|
| Order Phase I early | Commission a seller-side ASTM E1527-21 Phase I months before marketing to control the narrative. |
| Contracts don’t bind regulators | Indemnity clauses shift buyer/seller obligations but cannot block a CERCLA claim against a prior owner. |
| Size escrow to real risk | Base holdbacks on remediation estimate plus contingency, released against verified milestones. |
| Pursue regulatory closure | An NFA letter or VCP enrollment can shrink buyer holdback demands substantially. |
| Layer your protections | Combine indemnity, escrow, and pollution legal liability insurance rather than relying on one tool. |
Table of Contents
- What Legal Limits Apply to Environmental Liability Transfer?
- What Should Sellers Do Before Marketing a Contaminated Asset?
- Which Deal Structures Best Allocate Environmental Risk?
- How Does Contamination Affect Asset Valuation?
- How Can Sellers and Lenders Manage Residual Environmental Risk?
- How Does Maascompanies Support Environmental Liability Transactions?
- When Does Liability Transfer Beat Remediation-First?
- Sources
What Legal Limits Apply to Environmental Liability Transfer?
Contracts allocate risk between buyer and seller. They do not bind the Environmental Protection Agency or state regulators. Under CERCLA §107(e), a private indemnity agreement is enforceable between the parties, but it cannot be raised as a defense against a government cleanup order. If contamination surfaces years later, the agency can still pursue any prior owner or operator, regardless of what the sale contract says.
Buyers protect themselves differently: through the bona fide purchaser and innocent landowner defenses under CERCLA. Both require that the buyer complete All Appropriate Inquiries (AAI) before closing, satisfied in practice by a Phase I ESA conducted to the ASTM E1527-21 standard. Skip that step, or let the report go stale, and the buyer loses statutory protection, which usually kills the deal or drives the price down.
Permit transfers add another layer of friction. RCRA hazardous waste permits and most state environmental permits do not transfer automatically; they typically require regulatory review and, in some cases, financial assurance from the new owner. A few factors materially reduce this friction:
- A regulatory No Further Action (NFA) letter already on file
- Active enrollment in a state VCP with a defined closure timeline
- Clean permit history with no open violations
What Should Sellers Do Before Marketing a Contaminated Asset?
Preparation determines who controls the narrative during due diligence. Sellers who wait for a buyer’s environmental consultant to find problems lose leverage immediately and often absorb last-minute price cuts.
- Commission a seller-side Phase I ESA early. This is the single highest-value pre-sale action available, and it lets you frame findings on your own timeline rather than reacting to a buyer’s report.
- Set clear triggers for Phase II testing. If the Phase I identifies a recognized environmental condition (REC), order subsurface sampling before marketing begins, not after a buyer requests it mid-negotiation.
- Assemble the regulatory file. Pull permits, closure letters, spill reports, and historical operating records into one due diligence package.
- Get a remediation cost estimate. Even a preliminary scope-and-cost estimate lets you evaluate whether targeted remediation or VCP enrollment makes sense before you go to market.
- Draft your disclosure schedules and indemnity terms in advance. Decide your target survival period, indemnity cap, and basket threshold before a buyer proposes their own.
Pro Tip: Order the Phase I months before you list the asset, not weeks. A rushed report invites buyers to challenge its scope, and a stale report (past its 180-day reliance window under standard practice) can force a costly update mid-negotiation.
Which Deal Structures Best Allocate Environmental Risk?
Asset sales generally limit successor liability exposure more than stock sales, since the buyer picks specific assets rather than inheriting the selling entity’s full liability history. That said, courts will disregard the distinction under the “mere continuation” or de facto merger doctrines if the buyer keeps the same operations, employees, and management with only the corporate shell changed.
Buyers price environmental risk mechanically: they take a remediation cost estimate and apply a contingency multiplier, commonly 1.5 to 2 times the estimate for uncharacterized conditions. That inflated number becomes the starting point for a price reduction or escrow demand.
For upside-down transactions, where cleanup costs exceed the property’s clean value, escrow structures tied to independent engineer verification let sellers fund remediation without simply handing over cash. Funds release in tranches only after the engineer confirms each milestone, protecting the seller from a buyer that stalls or defaults mid-cleanup.
A workable indemnity should specify:
- Exact scope of covered environmental claims
- Survival period tied to applicable statutes of limitation
- A cap sized to the realistic worst-case remediation estimate
- A basket threshold that screens out nuisance claims
- Who controls defense of third-party claims and how disputed costs get accounted for
How Does Contamination Affect Asset Valuation?
Two separate cost categories hit the price: the actual remediation bill, and market stigma, the discount buyers apply simply because a property carries a contamination history, even after cleanup. One academic case study on former industrial land found contamination and stigma effects combined to reduce property value by roughly 28.6 percent compared to a clean comparable, using residual and transformation valuation methods.
Sellers generally choose among three paths: complete remediation before marketing, accept a price adjustment at closing, or fund cleanup through a post-close escrow. Each fits a different situation.
| Scenario | Best-fit approach |
|---|---|
| Contamination is well-characterized, moderate cost | Pre-sale remediation to maximize price |
| Costs are uncertain or high | Price adjustment plus escrow holdback |
| Buyer has remediation expertise, seller needs speed | Escrow-funded post-close cleanup |
A simplified example: a plant with a multi-million dollar headline value carries a remediation estimate; applying a contingency multiplier typical for such cases, the buyer proposes an escrow holdback, leaving the seller with the net proceeds after accounting for remediation and escrow amounts, plus any unused escrow released later. An NFA letter or VCP closure obtained beforehand typically shrinks that holdback substantially, since it removes the contingency buffer buyers build in for the unknown.
How Can Sellers and Lenders Manage Residual Environmental Risk?
Insurance and financial assurance fill the gap that contracts alone cannot close. Pollution legal liability policies cover third-party bodily injury and cleanup claims; cost-cap policies protect against remediation running over budget; newly discovered conditions coverage addresses contamination nobody knew about at closing. Premiums vary widely, roughly 2 to 10 percent of coverage limits depending on site history and coverage scope.
Financial assurance options beyond insurance include escrow, letters of credit, surety bonds, and parent company guarantees. Structure releases against verified milestones, never fixed calendar dates.
Before accepting any buyer’s offer, screen for:
- Balance sheet capacity to fund remediation if costs run over
- Documented remediation experience on comparable projects
- Willingness to accept independent engineer oversight
- No history of walking away from environmental obligations on prior deals
Pro Tip: No single tool closes the gap alone. The transactions that hold up combine indemnity, escrow, and insurance, so if one layer fails, the other two still protect your net recovery.
How Does Maascompanies Support Environmental Liability Transactions?
Maascompanies has managed complex industrial dispositions where environmental documentation directly shaped buyer confidence and final price, including the orderly negotiated sale of GE surplus switchgear and the negotiated sale of used tire shredding equipment. Both required coordinated marketing to qualified industrial buyer pools who understood the assets and the associated risk profile.
A seller-commissioned Phase I, completed before marketing begins, shifts leverage back to the seller and keeps a buyer’s own consultant from dictating the price conversation.
Our process typically includes:
- Marketing to vetted, industry-specific buyer networks rather than general auction traffic
- Structuring orderly negotiated sales instead of forced liquidation pricing
- Coordinating escrow and milestone release schedules alongside independent engineer verification
- Screening buyer creditworthiness and remediation capacity before final award
Engage a marketing partner once your Phase I is complete and your regulatory file is assembled. That sequencing maximizes competitive tension among buyers who already trust what they are bidding on.
When Does Liability Transfer Beat Remediation-First?
Liability transfer makes sense when a business needs balance-sheet relief now, or when the asset is non-core and the buyer pool includes operators with genuine remediation expertise. Waiting rarely helps in those cases; carrying costs and regulatory exposure compound the longer the asset sits idle.
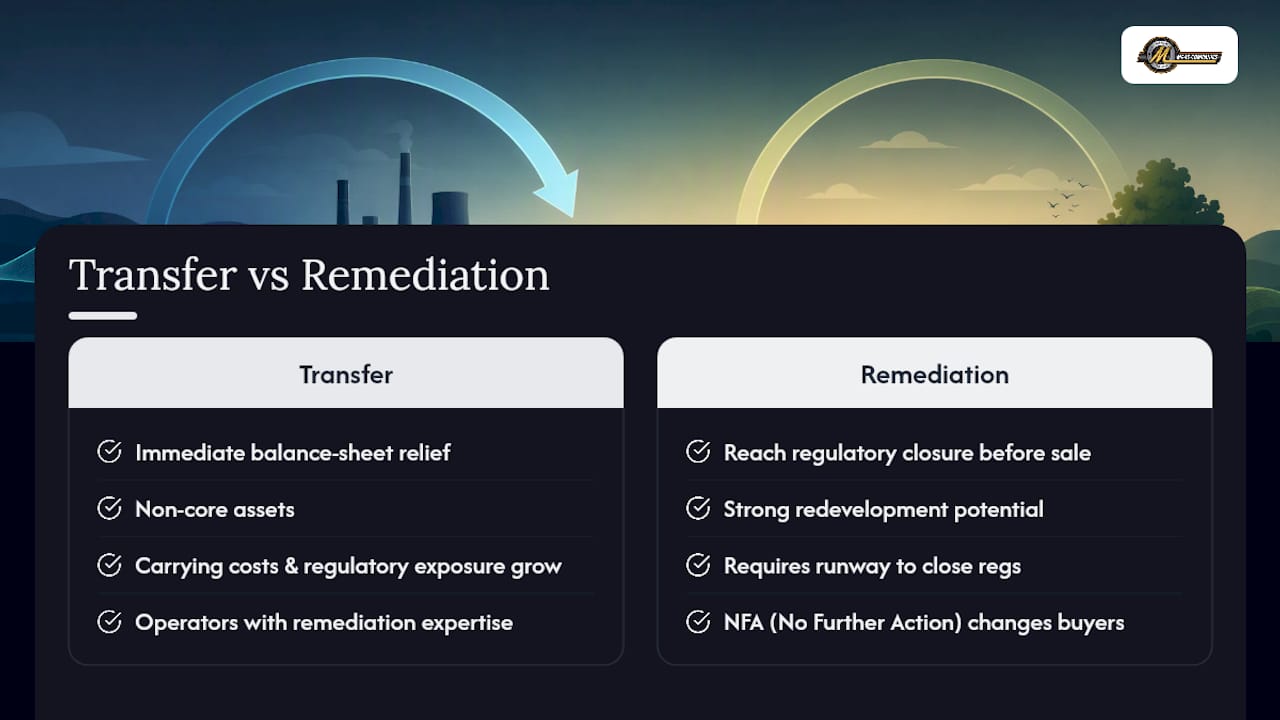
Remediation-first is the better call when a site has strong redevelopment potential and there is runway to reach regulatory closure before selling. An NFA letter in hand changes the buyer pool entirely.
What most owners underestimate: a marketing partner who understands industrial buyers doesn’t just find a buyer faster. It changes who shows up to bid, and that shift often matters more than any single contract clause.
— Vector
Sources
- Environmental Liability Transfers: Buyer and Seller Perspectives - Babst Calland
- Environmental Liability in M&A: How Buyers Price It and How Sellers - Glacier Lake Partners
- Environmental Liability - The Hidden Deal-Killer in Industrial Transactions - Exit Ready Advisors
Recommended
- Role of Private Equity in Asset Sales: Sponsor Playbook | Blog | Insights on Asset Liquidation and Auction Trends
- Facility Liquidation Strategies That Keep Transitions on Track | Blog | Insights on Asset Liquidation and Auction Trends
- Asset Sale Benefits 2026: A Strategic Guide for Sellers | Blog | Insights on Asset Liquidation and Auction Trends
- Definition of Bulk Asset Sales for Executives | Blog | Insights on Asset Liquidation and Auction Trends