Blog
Lease Architecture Matters: Industrial Sale Leaseback for Owners, CFOs

An industrial sale-leaseback lets an owner sell a facility to an investor and immediately lease it back, converting fixed real estate into working capital while operations continue uninterrupted. It makes the most sense when a company needs liquidity for debt reduction, capital expenditure, or growth but cannot justify tying that capital up in owned real estate. The trade-off is real: owners give up long-term control and take on a binding lease obligation in exchange for cash today.
TL;DR:
- Master lease structures simplify management but concentrate risk, making substitution rights and defect remediation critical in negotiations.
- Longer lease terms of 10 to 20 years with fixed escalations generally lead to higher sale prices, while shorter deals offer less predictability.
- Timing for a single-property sale-leaseback typically ranges from three to six months, but portfolio deals can take longer due to added coordination.
- Owner’s post-transaction responsibilities include lease administration, budgeting for maintenance, and monitoring renewal and substitution provisions.
- Effective marketing to institutional investors often results in better pricing than local sales, especially with a structured, competitive process.
Table of Contents
- What Is an Industrial Sale-Leaseback and How Does It Work?
- What Business Benefits Do Owners Gain From a Sale-Leaseback?
- What Are the Risks and Disadvantages of a Sale-Leaseback?
- Which Lease Terms Matter Most in Negotiation?
- How Long Does an Industrial Sale-Leaseback Take to Close?
- Is a Sale-Leaseback the Right Move for Your Company?
- Where Maas Companies Adds Value in a Sale-Leaseback Transaction
- How Are Industrial Sale-Leasebacks Priced and Structured?
- What Are the Tax Implications for Sellers and Investors?
- How Does a Sale-Leaseback Compare to Other Financing Options?
- How Should Owners Manage a Facility After the Sale-Leaseback Closes?
- Editorial Take: What the Conventional Sale-Leaseback Advice Misses
- Sources
What Is an Industrial Sale-Leaseback and How Does It Work?
The mechanics follow a set sequence. An owner prepares the property and financials for market, a broker or advisor markets the asset to institutional buyers, and the sale closes simultaneously with execution of a new lease. The seller becomes the tenant the moment the deed transfers, so operations never pause.
Owners choosing this path for industrial asset financing face a structural decision early: master lease or individual leases. That choice shapes everything from cross-default exposure to how easily a facility can later be substituted or sold out of the portfolio.
- Master lease structure: bundles multiple properties under one lease agreement, which simplifies administration for both parties but ties performance across all sites together.
- Individual leases: give each facility its own terms and remedies, offering more flexibility but requiring more legal and financing overhead.
- Single-property deals: move faster and involve simpler due diligence than multi-site transactions.
- Portfolio transactions: attract more aggressive investor interest and often better pricing, but negotiations take longer and involve more coordination among lenders and counsel.
Master leases simplify enforcement for investors managing a portfolio, but they concentrate risk. If one location underperforms or faces regulatory trouble, the whole lease can be affected, a trade-off worth weighing carefully before signing.
What Business Benefits Do Owners Gain From a Sale-Leaseback?
The primary draw is liquidity. Proceeds from an industrial sale-leaseback typically fund debt paydown, capital expenditure, or working capital, without adding a new loan to the balance sheet. Because the transaction converts an owned asset into an operating lease, it can also improve balance-sheet metrics that lenders and investors watch closely.
- Immediate cash without new secured debt or dilution of equity.
- Removal of a fixed asset from the balance sheet, which can improve return-on-assets calculations.
- Preserved operational continuity, since the seller keeps using the facility under a negotiated lease.
- Capital redeployment into core business activities rather than idle real estate.
Owners monetize real estate to reduce debt, strengthen the balance sheet, or fund reinvestment while retaining operational control through the leaseback, according to W. P. Carey’s analysis of industrial sale-leaseback appeal. That combination, cash now plus continued use of the site, is what distinguishes a leaseback from a traditional sale.
For companies weighing this against conventional lending, sale-leaseback strategy often produces more usable capital per dollar of asset value than a mortgage refinance, since a leaseback isn’t capped by loan-to-value ratios in the same way secured debt is.
What Are the Risks and Disadvantages of a Sale-Leaseback?
The benefits come with a binding cost: once the deed transfers, the owner is a tenant, subject to rent escalations, lease covenants, and restrictions it did not face as a property owner. Go-dark provisions, which restrict or penalize a tenant for ceasing operations at the site, can limit flexibility if business conditions change.
- Loss of long-term control over a facility the company may have built or customized over decades.
- Fixed lease obligations that persist regardless of business performance, with escalation clauses baked in.
- Landlord remedies triggered by tenant credit deterioration, which can include accelerated rent or lease default.
- Deal failure risk from valuation mismatches, unresolved environmental or title issues, or lenders withholding consent.
Deal failure commonly stems from those same practical problems, valuation gaps, unresolved environmental or title defects, and missing lender consent, according to industry guidance on sale-leaseback pitfalls. None of these are exotic risks. They are the ordinary friction points that derail transactions when due diligence starts too late.
Which Lease Terms Matter Most in Negotiation?
The purchase price gets the headlines, but the lease terms determine whether the deal serves the business for the next 10 to 20 years. Practitioners consistently find that negotiating master-lease architecture, cross-default provisions, substitution rights, and go-dark clauses matters more to long-term flexibility than the cap rate or sale price itself.
- Cross-default protections: Confirm that trouble at one facility in a portfolio deal cannot trigger default across every leased site.
- Substitution rights: Negotiate the ability to swap out an underperforming or obsolete property for another, subject to fair conditions.
- Appraisal triggers and caps: Set clear valuation benchmarks and caps so substitutions don’t become a point of dispute later.
- Maintenance and CAPEX allocation: Define who pays for roof, structure, and major system replacements versus routine upkeep.
- Environmental responsibility: Assign liability for pre-existing versus post-closing contamination clearly, in writing.
- Go-dark restrictions: Understand exactly what happens if the tenant needs to cease operations, temporarily or permanently, at the site.
A well-drafted substitution right should condition any replacement property on minimum appraised value, functional equivalence, and clear cost allocation to prevent tenant “cherry-picking” of only the best-performing assets.
Pro Tip: Push for substitution rights before you sign, not after. Once the lease is executed, your leverage to negotiate flexibility drops sharply, and investors have little incentive to reopen favorable terms.
How Long Does an Industrial Sale-Leaseback Take to Close?
A single-property transaction moves through a fairly predictable sequence, though portfolio deals stretch every phase.
- Preparation: Owner obtains an independent valuation, secures internal approvals, and confirms lender consent if the property carries existing debt.
- Marketing: Advisor or broker markets the asset to qualified institutional and private investors, generating competing offers.
- Letter of intent and due diligence: Buyer conducts Phase I (and Phase II if triggered) environmental assessments, structural and engineering reviews, and title searches.
- Lease negotiation: Both sides finalize master lease or individual lease terms, including the negotiation priorities covered above.
- Closing: Sale and lease execute simultaneously, funds transfer, and the seller continues operating as tenant of record.
Time-to-cash for a well-prepared single-property deal typically runs three to six months from mandate to closing, with portfolio transactions taking longer given the added coordination. Lender consent mechanics on substitution and replacement properties can materially extend closing timelines in multi-site deals, so bringing financing parties into the conversation early avoids late-stage surprises.
Is a Sale-Leaseback the Right Move for Your Company?
Not every owner should pursue this strategy, and the decision hinges on a few concrete tests rather than gut instinct.
- Financial test: Compare the loan-to-value ceiling of a refinance against the capital a leaseback would generate, then weigh the new rent obligation against your current cost of capital.
- Covenant test: Check whether removing the asset and adding a lease liability helps or hurts existing debt covenants.
- Operational test: Assess how critical the specific site is to your operations and whether heavy customization makes relocation impractical.
- Growth test: Consider whether planned expansion would be constrained by a fixed lease footprint.
- Governance test: Confirm lender approvals, review GAAP and ASC 842 lease accounting impacts with your accounting team, and secure board alignment before marketing the property.
Pro Tip: Run the numbers on lease-versus-cost-of-capital before you talk to a single buyer. If the implied rent exceeds what you’d pay in interest on equivalent secured debt, a leaseback may cost more than it delivers.
Where Maas Companies Adds Value in a Sale-Leaseback Transaction
Specialist marketing changes the outcome of an industrial sale-leaseback more than most owners expect. A facility marketed only to local buyers rarely draws the competitive tension that produces top-of-market pricing; a properly run process reaches institutional capital actively seeking industrial real estate sales opportunities, and that competition drives realized price.
Maascompanies works with owners to determine whether an orderly negotiated sale or a broader auction pathway fits the asset and timeline. A negotiated sale suits complex single-site properties where relationship-driven buyers matter; a wider marketing process suits assets with strong general market appeal, where casting a wide net maximizes competitive bidding.
What Maascompanies delivers is a structured marketing plan, a realistic timeline aligned to lender and stakeholder needs, and coordination across legal, environmental, and financing parties, all built around one goal: maximizing recovery for the seller. Fee structures are commission-based and tied directly to results, consistent with how industrial plant liquidation engagements are typically structured for lenders and special asset managers.
How Are Industrial Sale-Leasebacks Priced and Structured?
Pricing in an industrial sale-leaseback centers on two linked numbers: the sale price and the initial lease rate, usually expressed as a capitalization rate. Investors price the asset based on the tenant’s credit quality, the lease term length, and the property’s functional characteristics. They then set rent to deliver their target yield over the lease term.
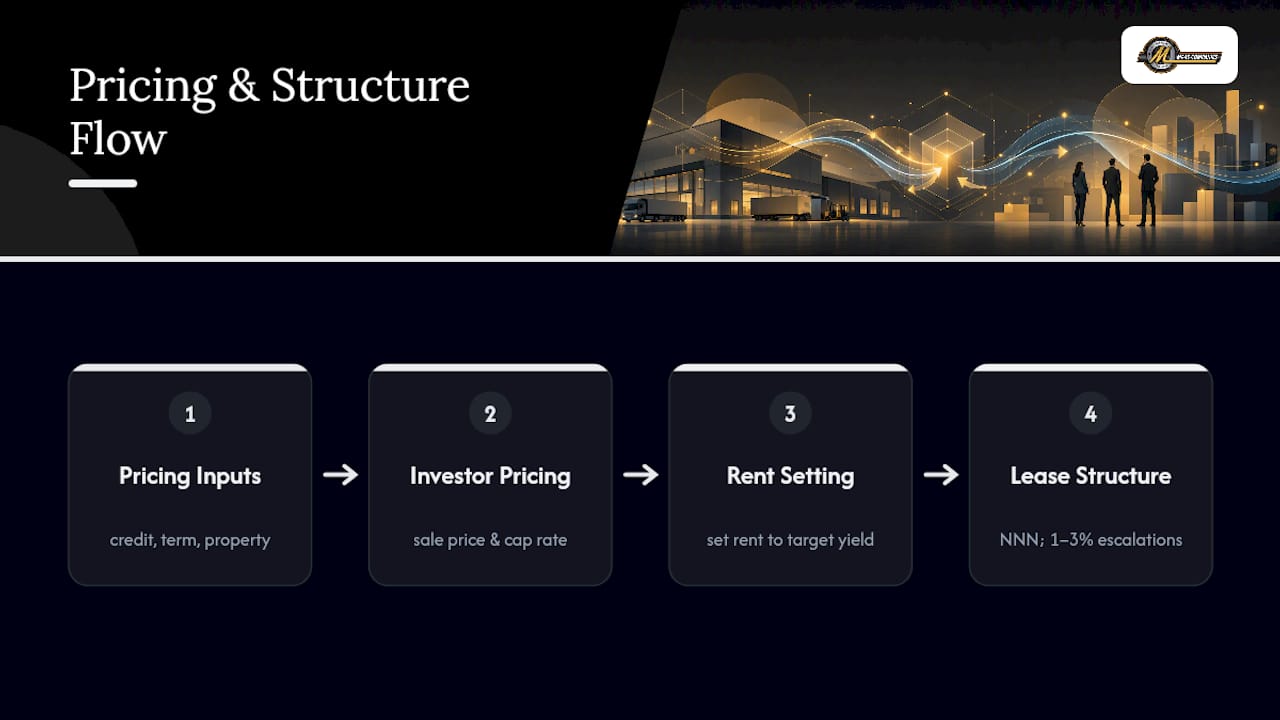
Longer lease terms, typically 10 to 20 years with renewal options, generally support higher sale prices because they give the investor more predictable income. Shorter terms shift more risk to the investor and typically produce a lower valuation for the seller. Rent structures usually include fixed annual escalations, often in the 1% to 3% range, or periodic adjustments tied to an index, giving the investor inflation protection over the lease term.
Most industrial sale-leasebacks use triple-net (NNN) lease structures, where the tenant covers property taxes, insurance, and maintenance directly. This keeps the investor’s return predictable and is a major reason cap rates in NNN industrial deals tend to run tighter than in gross-lease structures. Portfolio transactions introduce another pricing lever: investors often pay a premium for scale and geographic diversification, but they also negotiate harder on lease uniformity across sites to simplify future enforcement, an approach discussed in the context of large-scale industrial portfolio activity like the $628 million national industrial portfolio acquisition that closed recently. Sellers negotiating a single asset have less pricing leverage from scale but often retain more control over individual lease terms.
What Are the Tax Implications for Sellers and Investors?
Both sides of an industrial sale-leaseback face distinct tax consequences, and neither should finalize a deal without dedicated tax counsel reviewing the structure.
For the seller-tenant, the sale typically triggers a taxable gain if the sale price exceeds the property’s depreciated basis, and that gain can be substantial for facilities held for decades. Lease payments going forward are generally deductible as an operating expense, which can offset some of the tax impact over time, but the timing mismatch, a lump-sum gain now against deductions spread over years, is something finance teams need to model carefully rather than assume nets out favorably.
For the investor-landlord, the acquired property becomes a depreciable asset, and rental income is taxed as ordinary income offset by depreciation deductions and any interest expense if the purchase is leveraged. Under current lease accounting rules, both parties also need to evaluate classification under ASC 842, since how a lease is classified affects how it appears on the tenant’s balance sheet and can influence loan covenant calculations tied to leverage ratios.
Structuring a sale-leaseback around a 1031 exchange is sometimes viable for the seller if proceeds are reinvested in qualifying like-kind property, though this depends heavily on individual circumstances and timing rules that a tax advisor needs to confirm before the sale closes. None of these mechanics are optional reading. They shape whether the net proceeds from a leaseback actually deliver the liquidity an owner is counting on.
How Does a Sale-Leaseback Compare to Other Financing Options?
Owners typically weigh a sale-leaseback against three alternatives: a traditional outright sale and relocation, conventional mortgage refinancing, or an equipment or asset-based lending facility.
A traditional sale without a leaseback generates cash but forces relocation, which is often impractical for facilities with heavy equipment installations, specialized utility infrastructure, or workforce ties to a specific location. It also introduces operational disruption that a leaseback avoids entirely.
Mortgage refinancing keeps ownership intact but is capped by loan-to-value limits, typically 65% to 75% for industrial property, meaning owners leave equity untapped that a sale-leaseback could convert fully into cash. Refinancing also adds a new debt obligation to the balance sheet, the opposite of the deleveraging effect a leaseback produces.
Asset-based lending against equipment or receivables can supplement liquidity needs but rarely matches the capital a real estate sale-leaseback generates, since it is limited to a fraction of the collateral’s value and carries higher relative interest costs. For owners whose primary asset is the facility itself rather than equipment, a leaseback is often the more efficient lever.
The right choice depends on how critical continued site occupancy is, how much capital is needed, and how much balance-sheet flexibility the company requires going forward. Owners planning eventual relocation or facility consolidation may find a traditional sale cleaner; owners planning to stay put indefinitely usually get more value from the leaseback structure.
How Should Owners Manage a Facility After the Sale-Leaseback Closes?
Closing the transaction is the beginning of a new relationship, not the end of the process. As tenant, the former owner now answers to lease administration requirements that didn’t exist under outright ownership.
Track lease escalation dates, renewal option deadlines, and any reporting obligations tied to financial covenants the landlord requires. Missing a renewal notice window can forfeit valuable occupancy rights, sometimes with no recourse. Under a triple-net structure, the tenant typically manages day-to-day property maintenance directly, which means budgeting for roof repairs, HVAC replacement, and paving well before those costs hit, since deferring maintenance can trigger default provisions in some leases.
Maintain clear records of any capital improvements made to the facility post-closing, particularly if the lease includes provisions for tenant-funded upgrades or landlord reimbursement of certain capital items. Coordinate with the landlord proactively on any operational changes, expansion, subleasing part of the space, or equipment installations that might affect the property, since most leases require landlord consent for material changes.
Finally, revisit the lease terms periodically against business plans. A facility that fit operations perfectly at signing may not fit five years later, which is exactly why substitution rights and renewal flexibility, negotiated at the outset, matter as much after closing as they did during the transaction itself.
Editorial Take: What the Conventional Sale-Leaseback Advice Misses
Most guidance on industrial sale-leasebacks fixates on price, the cap rate, the multiple, the headline number a broker can put in a pitch deck. That emphasis is backwards. The research on this topic points consistently toward lease architecture, not price, as the variable that determines whether a leaseback helps a company or quietly constrains it for two decades.
Owners who negotiate hard on sale price but accept boilerplate lease language on substitution, cross-default, and go-dark provisions are trading a known, one-time cost for an unknown, recurring one. The evidence points to master lease structures as attractive to investors precisely because they simplify enforcement, which is a euphemism for concentrating risk onto the tenant’s side of the table.
The right priority order is: understand the operational commitment the lease creates, then negotiate the sale price. Owners and CFOs who reverse that sequence rarely notice the mismatch until year three, when a go-dark clause or a rigid substitution formula limits a decision the business actually needs to make.
— Vector
Sources
- Portfolio architecture and operational flexibility in industrial sale-leasebacks: Structuring for the long game | Law Journal Newsletters
- Top 10 Things to Know About Sale-Leasebacks | MFG
- Partnership acquires national industrial portfolio for $628M | REBusinessOnline