Blog
Phase I ESA Requirements: What CRE Deal Teams Must Know

A compliant Phase I Environmental Site Assessment must satisfy ASTM E1527-21 and EPA’s All Appropriate Inquiries rule under 40 CFR Part 312, and it must be signed by a qualified Environmental Professional. Meet both standards and the report secures lender acceptance and CERCLA liability protection. Miss either one, and the report may not hold up during underwriting or in a future liability dispute.
The deliverables are consistent across nearly every commercial transaction:
- A records and regulatory database search covering federal, state, and local environmental listings
- Historical research into prior site use (Sanborn maps, aerial photos, city directories)
- A physical site reconnaissance with photographic documentation
- Interviews with owners, occupants, and local government officials
- A written report with a clear Recognized Environmental Condition (REC) determination
- Certification signed by the Environmental Professional who takes responsibility for the findings
A Phase I report is generally considered reliable for several months from completion, and most lenders require a full refresh after about a year. Closing timelines that stretch past those windows need an update, not a fresh start from scratch, but the distinction matters for budget and schedule.
Key Takeaways
A compliant Phase I ESA requires ASTM E1527-21 methodology, EPA AAI documentation under 40 CFR Part 312, and certification by a qualified Environmental Professional to preserve lender acceptance and CERCLA protection.
| Point | Details |
|---|---|
| Standard and rule | Require ASTM E1527-21 compliance plus EPA AAI documentation under 40 CFR Part 312 in every scope of work. |
| EP qualification | Verify the Environmental Professional’s CV, license or certification, and insurance before engagement, not after. |
| Report shelf life | Treat 180 days as the reliability window and one year as the outer limit before a full refresh is needed. |
| Budget and schedule | Plan for $2,200 to $4,000 and a 2 to 3 week turnaround on standard commercial sites, more for industrial properties. |
| Coordinated diligence | Maas Companies sequences environmental consultants within the sale timeline to protect closing dates and recovery value. |
Table of Contents
- Phase 1 ESA Requirements Under ASTM E1527-21 and EPA AAI
- Who Can Perform a Phase I ESA: the Environmental Professional Requirement
- What Triggers a Phase I ESA in a Commercial Transaction
- The Phase I ESA Process: Records, Site Visit, Interviews, and Reporting
- How Long Is a Phase I ESA Valid Before It Needs an Update?
- Phase 1 ESA Cost and Turnaround Time
- Lender and Federal Program Acceptance Criteria
- When RECs Are Found: The Phase II Path and What Happens Next
- How Maas Companies Supports Environmental Diligence in Asset Sales
- Why Environmental Diligence Discipline Protects Recovery Value
- Maas Companies Services for Transactions Requiring Environmental Diligence
- Sources
Phase 1 ESA Requirements Under ASTM E1527-21 and EPA AAI
ASTM E1527-21 is the operative standard practice for Phase I work in the United States, and it is what most lenders, courts, and government agencies mean when they ask for a “Phase I ESA.” The 2021 revision tightened historical research obligations, added explicit consideration of emerging contaminants such as PFAS, and requires reviewers to check for environmental liens and activity/use limitations recorded against the property. A report built to an older version of the standard, or to a consultant’s informal template, will not carry the same CERCLA weight.
EPA’s AAI rule under 40 CFR Part 312 is the federal regulation that ties the ASTM practice to legal liability protection. Complete your due diligence to AAI standards, and you preserve access to the innocent landowner, bona fide prospective purchaser, and contiguous property owner defenses under CERCLA. Skip a required step, and that protection can evaporate even if the property turns out to be clean.
The required scope generally includes:
- A search of federal databases (National Priorities List, RCRA, CERCLIS) alongside state environmental agency records and local fire department or health department files
- Review of historical land use records going back to the property’s first developed use, not just the last several decades
- On-site inspection documenting current conditions, adjoining property use, and any visual evidence of contamination
- Interviews with current owners, key site personnel, and local government officials familiar with the property’s history
RECs, CRECs, and HRECs are not interchangeable terms, and a report that conflates them creates ambiguity a lender’s counsel will flag. A REC is a current or likely release of hazardous substances. A Controlled REC (CREC) is a past release addressed to a regulatory closure standard but still subject to controls (deed restrictions, land use limits). A Historical REC (HREC) is a past release that has been fully remediated to unrestricted use standards.
Pro Tip: State environmental databases vary widely in how far back they go and how well they are indexed. If your target property sits in a state with known gaps in its environmental records (common in older industrial corridors), specify supplemental local record searches in your scope of work rather than relying on the consultant’s default database package.
Who Can Perform a Phase I ESA: the Environmental Professional Requirement
The Environmental Professional (EP) designation under 40 CFR 312.10 is not a courtesy title. It is a federal regulatory qualification, and the person who signs your report has to meet it or the report’s CERCLA protections are at risk.
The regulation defines an EP through one of several qualifying paths: a state certification in environmental site assessment plus relevant experience, a professional engineering or geologist license plus experience, or a bachelor’s degree in a science or engineering field combined with a set number of years of relevant environmental assessment experience (the threshold rises for those without a qualifying degree). The EP must personally review and sign the certification statement; that responsibility cannot be delegated to junior field staff or an unlicensed project coordinator.
Before you engage a consultant, ask for documentation that proves EP status, not just a firm’s marketing materials:
- The EP’s current CV or resume showing qualifying education and experience
- Proof of professional license or state certification, where applicable
- Confirmation of errors and omissions insurance coverage
- A sample certification page from a prior report showing the EP’s actual signature, not a firm stamp
What Triggers a Phase I ESA in a Commercial Transaction
Most Phase I orders come from one of a handful of predictable events, and knowing which trigger applies determines how much flexibility you have on scope and timing.
- Property acquisition or sale. Buyers order a Phase I to preserve CERCLA innocent landowner protections; sellers increasingly commission one proactively to control the narrative before a buyer’s consultant does.
- Conventional lending and refinancing. Most commercial lenders require a current Phase I before closing, and many require an update at refinance even if a report already exists.
- Federal loan programs. SBA 504 and 7(a) loans, HUD multifamily and healthcare financing, and USDA Rural Development loans each carry their own environmental review requirements that generally reference AAI compliance, sometimes with program-specific checklists layered on top.
- Portfolio and bulk transactions. Multi-property deals sometimes use a tiered approach, full Phase I on higher-risk assets and a more limited desktop review on lower-risk ones, but lenders financing the deal will usually dictate the minimum acceptable scope.
- Enhanced scope situations. Prior industrial use, known nearby contamination, or a REC from an earlier report can push a transaction toward a broader assessment before anyone commits capital.
The Phase I ESA Process: Records, Site Visit, Interviews, and Reporting
The consultant’s records review starts with the regulatory database search, typically pulled from a commercial data vendor covering federal and state lists, and moves into historical sources: Sanborn fire insurance maps, aerial photographs, city directories, and prior environmental reports if any exist. Reliability of the database vendor matters. Established environmental data providers cross-reference multiple government sources and flag data currency issues, while cut-rate search services sometimes miss recently listed sites.
- Records and historical research. The EP compiles chain-of-title information, prior use records, and any existing environmental reports on the property or nearby parcels.
- Regulatory database search. A vendor-run search of federal, state, and local environmental databases identifies listed sites within the required search radius (radius varies by database type under ASTM E1527-21).
- Site reconnaissance. The EP or trained field staff physically walk the property, documenting current and past uses, storage tanks, staining, drums, vents, and signs of dumping, with photographs tied to a site map.
- Interviews. The EP interviews current owners and occupants, and reaches out to local fire, health, or building officials who may hold non-public information about prior incidents.
- Report drafting. The written report synthesizes findings into a REC determination, with plain-language conclusions such as “no RECs identified” or “the presence of a former dry cleaner at the adjacent parcel constitutes a REC requiring further investigation.”
Pro Tip: Ask to review the draft report’s conclusions section before the final version is issued. A well-run consultant will walk you through any REC language in advance so there are no surprises when the lender’s underwriting team reads it for the first time.
How Long Is a Phase I ESA Valid Before It Needs an Update?
Report currency is a scheduling problem as much as a technical one, and it catches deal teams off guard more often than any other part of the process.
- The 180-day window is the tighter benchmark. Reports older than 180 days generally need at least a limited update before a lender or the AAI rule will treat them as reliable for the transaction.
- One year is the outer limit for most practitioners, reflecting long-standing EPA AAI guidance treating older reports as unreliable without a fresh full assessment.
- A limited-scope update typically covers a fresh regulatory database search, a check for new activity/use limitations, and confirmation that no site conditions have changed. It costs and takes far less than starting over.
- A full refresh is warranted when the closing has slipped more than a year past the original report date, when the property has changed hands or use in the interim, or when new contamination information has surfaced nearby.
Many experienced deal teams handle this by ordering a desktop update at contract signing and scheduling a full refresh only if closing slips past the one-year mark, a practice that keeps carrying costs predictable on longer transactions.
Phase 1 ESA Cost and Turnaround Time
Budget and schedule assumptions drive more procurement mistakes than any technical requirement in this process.
Typical Phase I ESA costs for standard commercial properties run between $2,200 and $4,000, with complex industrial or brownfield sites running higher due to more extensive historical research and larger regulatory search radii. Turnaround for a standard site is generally 2 to 3 weeks from order to final report.
Cost and schedule drivers worth budgeting around:
- Site size and complexity (a former manufacturing plant takes longer to research than a strip retail center)
- Number of adjoining and nearby properties requiring database review
- Availability of historical records (organized prior reports speed research; missing chain-of-title slows it)
- Rush requests, which carry premium fees and still cannot skip required steps
Before signing a proposal, confirm the scope of work explicitly cites ASTM E1527-21 compliance, that the consultant carries adequate insurance, and that they can supply references from comparable commercial transactions. Rushed timelines are achievable when a seller hands over organized historical materials and the consultant uses premium database vendors, but the underlying steps still have to happen in full.
Lender and Federal Program Acceptance Criteria
Underwriters and program reviewers work from checklists, and a report that misses one item can bounce back for correction days before a scheduled closing.
- Confirm ASTM E1527-21 compliance is stated explicitly in the report, not implied
- Verify the EP’s certification signature appears on the report, matched against CV documentation the lender may separately request
- Check that the report date falls within the lender’s reliance window, generally 180 days, occasionally extended with a documented update
- Review any lender-specific addenda; many institutional lenders and all three federal programs (SBA, HUD, USDA) layer their own requirements on top of the baseline ASTM scope
- Confirm the report addresses vapor intrusion and emerging contaminants if the property type or history calls for it
When a report identifies a REC, underwriting does not automatically stop, but it does change. Most lenders will require either a Phase II investigation resolving the finding, a risk-based closure plan, or a price and escrow adjustment before funding proceeds. Federal program reviewers tend to be less flexible than conventional lenders on this point.
When RECs Are Found: The Phase II Path and What Happens Next
A REC finding does not kill a deal, but it does change its shape; employing effective ambient dust control for manufacturing plants can be a critical part of managing environmental conditions during assessment. Phase I assessments are non-intrusive by design; confirming or ruling out an actual release requires a Phase II investigation involving soil borings, groundwater sampling, or soil vapor testing, followed by laboratory analysis and an interpretive report.
- Scope the Phase II around the specific REC, not the whole property; targeted sampling near a former underground storage tank costs and takes far less than a blanket investigation.
- Negotiate remediation responsibility and cost allocation early. Escrow holdbacks, price reductions, and seller-funded remediation are all common resolutions, and each affects closing timing differently.
- Sequence the Phase II to protect the closing date. Starting sampling work the moment a REC is flagged, rather than waiting for final contract terms, preserves schedule leverage for every party at the table.
How Maas Companies Supports Environmental Diligence in Asset Sales
Coordinating a Phase I ESA inside an active auction or negotiated sale is a scheduling and disclosure problem as much as a technical one, and it is where deal timelines most often slip.
- Maas Companies coordinates environmental consultant selection and scheduling within the broader marketing and auction timeline, rather than treating diligence as a separate, disconnected workstream
- Disclosure of REC findings gets built into buyer materials at the right point in the process, reducing last-minute contingency disputes during court-ordered and lender-ordered sales
- Vendor coordination across appraisal, environmental, and legal teams keeps carrying costs from compounding while diligence runs its course
Integrating the Phase I timeline into the marketing and buyer disclosure schedule reduces buyer contingency disputes and preserves asset value, and coordinated vendor scheduling of this kind shortens time to close on industrial and court-ordered sales.
Maas Companies’ work spans plant closures, lender foreclosures, and government-ordered liquidations where environmental diligence sits directly on the critical path to a completed sale. Review the industrial property disposition process for how these steps fit into a broader liquidation timeline.
Why Environmental Diligence Discipline Protects Recovery Value
Environmental findings shape a transaction long before closing, and treating a Phase I as a compliance checkbox rather than a marketing variable is where sellers lose recovery value. A REC disclosed late, after buyers have already anchored on a price, invites renegotiation from a position of weakness. A REC disclosed early, with a clear scope of remediation or a documented closure plan attached, gets priced in rationally instead of used as leverage.
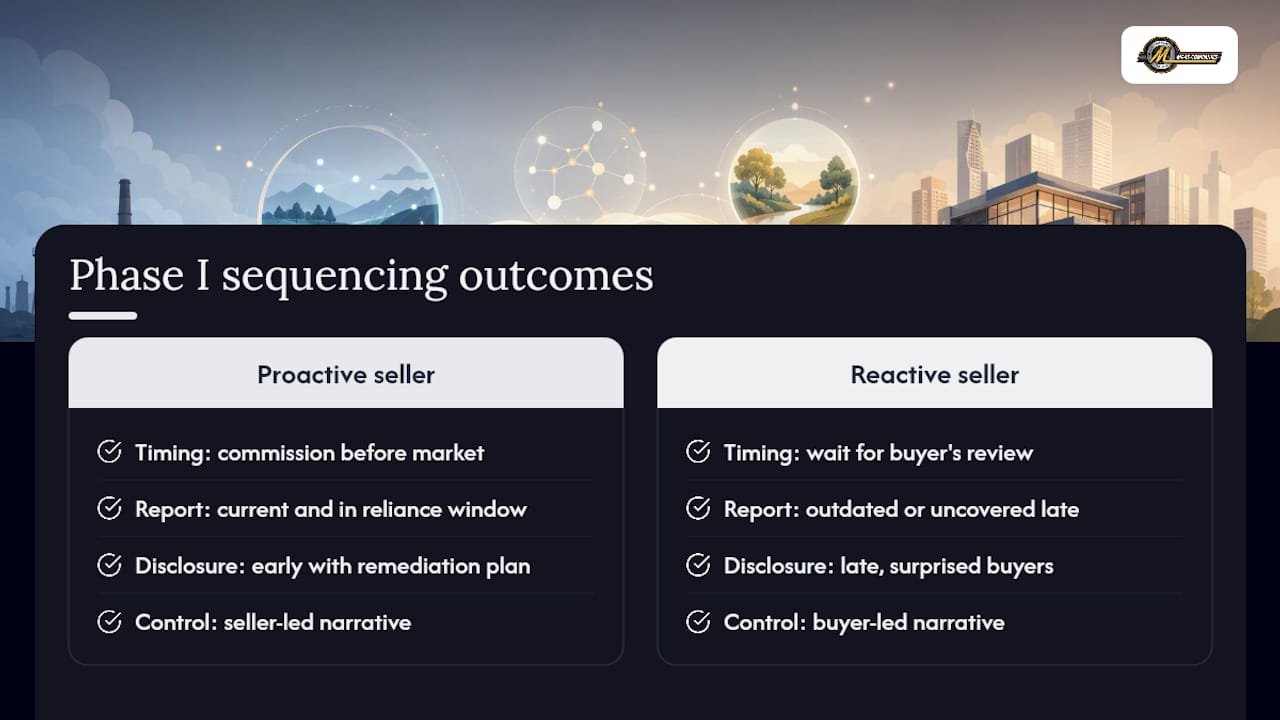
The gap between a smooth closing and a stalled one usually comes down to sequencing, not the underlying environmental condition itself. Sellers who commission a current Phase I before going to market, and who keep that report inside its reliance window through closing, give buyers and lenders one less reason to hesitate or renegotiate. Sellers who wait for a buyer’s consultant to surface issues lose control of the narrative and the timeline both.
Coordinating environmental consultants alongside the auction or negotiated sale calendar, rather than as an afterthought bolted onto due diligence, is what keeps a REC finding from becoming a closing crisis. That coordination, timing disclosure to buyer readiness and keeping report validity intact through the transaction, is where an experienced asset recovery partner earns its role. Reach out to discuss how a specific plant closure, restructuring, or lender-ordered sale should sequence its environmental diligence.
— Vector
Maas Companies Services for Transactions Requiring Environmental Diligence
Maas Companies gives sellers and lenders a coordinated path through transactions that carry environmental diligence requirements, without the delay of managing consultants, disclosure timing, and auction scheduling as separate workstreams.
For plant closures, lender-ordered sales, and government foreclosure liquidations, that coordination covers vendor procurement for environmental consultants, scheduling the Phase I or Phase II around the marketing calendar, and structuring buyer disclosures so REC findings do not derail a closing date. Clients get a single point of project management across appraisal, environmental, and legal workstreams instead of chasing three vendors on three separate schedules. That structure keeps carrying costs from compounding while diligence runs and preserves negotiating leverage instead of ceding it to a buyer’s consultant. Review the equipment brokerage and auction services for sellers to see how Maas Companies structures a coordinated disposition, or explore the full marketing and transaction services portfolio to discuss a specific plant closure, restructuring, or lender-ordered sale timeline.
Sources
- Use of the ASTM E1527-21 Phase I Environmental Site Assessment Standard Practice Is Now Required to Meet CERCLA Liability Protections
- ASTM E1527-21 standard
- Phase 1 Environmental Site Assessment Cost (2026 Guide)
- Phase I Environmental Site Assessment (ESA) Overview
Recommended
- How to Assess Real Estate Deals: A Professional Guide | Blog | Insights on Asset Liquidation and Auction Trends
- Pre-Auction Selling Checklist for Industrial Equipment | Blog | Insights on Asset Liquidation and Auction Trends
- Role of Private Equity in Asset Sales: Sponsor Playbook | Blog | Insights on Asset Liquidation and Auction Trends
- Industrial Real Estate Checklist: 2026 Investor Guide | Blog | Insights on Asset Liquidation and Auction Trends