Blog
What a Section 363 Sale Means for Corporate Asset Recovery

A Section 363 sale is a court-approved bankruptcy sale that lets a debtor sell assets free and clear of liens on an expedited timetable, making it the principal tool to maximize recovery for distressed U.S. corporate assets. The authority comes directly from Section 363 of the Bankruptcy Code, which permits a debtor in possession, or a trustee, to sell property outside the ordinary course of business with bankruptcy court approval.
For executives and lenders weighing options during a plant closure or restructuring, three implications matter immediately:
- The sale can strip away liens, claims, and encumbrances under §363(f), delivering the buyer clean title.
- A federal judge’s approval order gives the transaction finality that a private, out-of-court sale cannot match.
- The typical timeline runs 30 to 90 days from filing the bid procedures motion to closing.
That speed, paired with statutory protection, is why distressed companies and their creditors turn to this process before value erodes further.
Key Takeaways
A Section 363 sale maximizes recovery for distressed U.S. assets by combining court-ordered finality with a marketing timeline aggressive enough to generate real bidder competition.
| Point | Details |
|---|---|
| Statutory foundation | §363(f) permits free-and-clear transfers when one of five conditions, such as lienholder consent or price exceeding liens, is met. |
| Realistic timeline | Expect 30 to 90 days from bid procedures motion to closing, timing varies with asset complexity and creditor cooperation. |
| Buyer protections | §363(m) shields good-faith purchasers from successor-liability claims once the sale order is entered. |
| Stalking horse tradeoffs | Break-up fees set a bidding floor but can chill competition if sellers make them too generous. |
| Execution matters most | Firms like Maas Companies drive recovery by starting buyer outreach before court approval, not after. |
Table of Contents
- How Does a Section 363 Sale Process Work?
- What Legal Rules Govern a Section 363 Bankruptcy Sale?
- How Should Sellers Prepare for a Section 363 Sale?
- What Should Buyers Know Before Bidding on 363 Assets?
- What Role Does a Stalking Horse Bidder Play?
- What Is a Realistic Timeline for a Section 363 Sale?
- Why Maas Companies’ Experience Matters in 363 Sales
- What Happens to Liabilities After a Section 363 Sale Closes?
- How Does a 363 Sale Compare to a Plan Sale or a Private Sale?
- What Objections Commonly Arise During a 363 Sale?
- What Kinds of Assets Get Sold Through Section 363?
- Where the Conventional Advice on 363 Sales Falls Short
- Working With Maas Companies on a Court-Supervised Sale
- Primary Sources for Section 363 Sale Guidance
- Sources
How Does a Section 363 Sale Process Work?
The mechanics follow a predictable sequence, though the pace varies with asset complexity and creditor cooperation.
- Bid procedures motion. Debtor’s counsel files a motion asking the court to approve auction rules, notice requirements, and bidder qualifications.
- Marketing period. The debtor, often working with an asset recovery firm or investment bank, contacts prospective buyers and opens a data room.
- Bid deadline. Interested parties submit qualified bids meeting the criteria the court approved.
- Auction. If more than one qualified bid arrives, the debtor conducts a live or virtual auction to drive up price.
- Sale hearing. The court reviews the winning bid, hears objections, and enters a sale order.
- Closing. Funds transfer, the order becomes final, and assets change hands.
Each party carries distinct incentives. Debtor counsel wants a defensible record showing sound business judgment. Investment bankers or asset marketers want maximum bidder turnout. Secured creditors want confirmation that proceeds satisfy their liens or that adequate protection covers any shortfall. The court wants a transparent, arm’s length process it can approve without inviting appeal.
The tension throughout is speed versus thoroughness: a longer marketing window usually raises price, but carrying costs, employee attrition, and market drift punish delay.
What Legal Rules Govern a Section 363 Bankruptcy Sale?
Section 363 of the Bankruptcy Code gives the debtor or trustee authority to sell property outside the ordinary course of business, subject to court approval. The statute itself governs notice, hearing requirements, and adequate protection for parties with an interest in the property being sold.
Free-and-clear transfers under §363(f) require satisfying at least one of five conditions:
- Applicable non-bankruptcy law permits a sale free of the interest.
- The lienholder consents.
- The price exceeds the aggregate value of all liens on the property.
- The interest is subject to a bona fide dispute.
- The lienholder could be compelled to accept a money satisfaction.
Courts evaluate the debtor’s decision to sell under a business-judgment standard, first articulated in the Lionel line of cases, asking whether the sale serves a sound business purpose. Secured lenders who object typically negotiate adequate protection, cash collateral use, or lien attachment to sale proceeds instead of blocking the transaction outright.
Section 363(m) then protects a good-faith purchaser: once the sale order is entered and not stayed on appeal, the buyer keeps the asset even if the underlying approval is later challenged. That good-faith finding, paired with the court’s sale order, is what gives buyers the confidence to bid aggressively on a compressed schedule.
How Should Sellers Prepare for a Section 363 Sale?
Corporate sellers who treat a 363 sale as a fire sale leave money on the table. The debtors who recover the most treat it as a structured, marketed transaction with a hard deadline.
- Confirm the business-judgment case. Document why a court-supervised sale, rather than a private workout or liquidation, maximizes recovery for this specific asset pool.
- Package and value the assets. Segment real estate, equipment, and inventory separately if that produces higher aggregate recovery than a single lot sale, and build a data room before soliciting bids.
- Draft the bid procedures motion carefully. Define qualified-bid criteria, deposit requirements, and the auction format in a way credible bidders will actually clear.
- Manage notice and cure claims. Executory contracts and leases carried into the sale under §365 require cure amounts and adequate-assurance showings, which buyers scrutinize closely.
- Set the bid deadline two to three weeks before the auction. That window gives serious bidders time to complete diligence without letting momentum stall.
Debtors retain meaningfully more control in a 363 sale than they would in a Chapter 7 liquidation, and that control lets management shape auction terms to preserve going-concern value rather than simply maximizing scrap price. Firms experienced in bankruptcy asset sale procedures generally start marketing before the bid procedures motion is even approved, so momentum exists the moment the court sets deadlines.
Pro Tip: Calibrate qualified-bid criteria before you file the motion. Standards that are too loose invite unqualified bidders who waste auction time; standards that are too tight draw creditor-committee objections for chilling competition.
What Should Buyers Know Before Bidding on 363 Assets?
Bidders who assume a 363 sale works like a normal M&A transaction get outmaneuvered fast. Assets sell “as-is, where-is,” with limited representations and warranties. There is no seller indemnity to fall back on after closing, and no post-closing purchase price adjustment to fix a valuation dispute.
Sophisticated buyers price the clean-title value the sale delivers rather than expecting the contractual protections a healthy-company acquisition would include. That tradeoff, fast and final versus fully protected, is the defining feature of bankruptcy buying.
Before bidding, a serious buyer should:
- Arrange committed or bridge financing early; auctions rarely accommodate financing contingencies.
- Prioritize title and lien review, environmental exposure, and any cure liabilities tied to assumed contracts.
- Confirm assignment mechanics for leases and permits that transfer with the asset.
- Build a bid that leads with cash certainty and closing speed, since courts and debtors both weight execution risk heavily.
Pro Tip: Read the bid procedures order line by line before submitting a deposit. It tells you exactly what makes a bid “qualified,” and missing one requirement can disqualify an otherwise winning offer. Buyers preparing competitive numbers often study auction bidding tactics for distressed assets before finalizing their strategy.
What Role Does a Stalking Horse Bidder Play?
A stalking horse bidder sets the floor price for the auction, and the debtor typically negotiates a break-up fee or expense reimbursement to compensate that bidder for the diligence work of establishing terms other parties will now bid against.
The arrangement carries risk on both sides:
- Stalking horse bidders risk overpaying if no competing bids materialize, since they committed early without full market feedback.
- Debtors risk insufficient competition if the break-up fee or bid increments are set so generously that other bidders decline to compete.
- Qualified-bid criteria need to be narrow enough to exclude speculative or unfinanced offers, but broad enough that real buyers aren’t discouraged from participating.
Drafting these terms is a balancing act. A break-up fee in the 2 to 3 percent range of purchase price is common practice, though courts scrutinize fees that appear designed to entrench the initial bidder rather than genuinely compensate for the value that bidder’s opening offer created.
What Is a Realistic Timeline for a Section 363 Sale?
Timelines compress or stretch based on asset complexity, the number of secured parties, and whether regulatory clearance is required.
| Case Type | Typical Window | Key Driver |
|---|---|---|
| Expedited (single asset, clear title) | 30 to 90 days | Minimal creditor disputes, no antitrust review |
| Mid-market (multiple asset classes) | 45–90 days | Data room preparation, cure claim resolution |
| Regulated or complex industrial assets | 30 to 90 days | HSR Act filings, environmental permits, union issues |
The core checkpoints stay constant regardless of window length: bid procedures hearing, bid deadline, auction, sale hearing, entry of the sale order, and closing. When a transaction implicates antitrust concerns, HSR Act notification to the FTC and DOJ can add a mandatory waiting period that pushes closing past the debtor’s preferred date, so counsel should flag that exposure during the earliest case planning conversations.
Why Maas Companies’ Experience Matters in 363 Sales
Maas Companies Inc. has built its practice around marketing and selling industrial plants, equipment, real estate, and commercial property, including specialized work on court-ordered, lender-ordered, and government foreclosure liquidations.
- Representative engagements span manufacturing, energy, hospitality, healthcare, education, agriculture, and contractor equipment fleets.
- Project work includes complex, specialized equipment sales such as the orderly negotiated sale of a Crown Iron Works cornmeal desolventizer and toaster, illustrating the technical marketing knowledge court-supervised sales often require.
- Buyer outreach is built around targeted industry lists and aggressive advertising, not a passive listing posted and left alone.
A 363 sale only maximizes recovery if the auction actually draws qualified, motivated bidders. Getting the right buyers to the table before the bid deadline is the difference between a court-approved formality and a genuinely competitive sale.
What Happens to Liabilities After a Section 363 Sale Closes?
The sale order does more than transfer title. It defines exactly which liabilities travel with the assets and which stay behind with the bankruptcy estate.
Liens, claims, and encumbrances that satisfy one of the §363(f) prongs get stripped away at closing, leaving the buyer with clean title. That is the entire commercial point of structuring the transaction this way rather than through a private sale. Successor-liability claims, meanwhile, are generally cut off by the good-faith purchaser finding under §363(m), which protects a buyer who negotiated at arm’s length even if the sale order is later challenged on appeal, so long as the sale wasn’t stayed.
Secured creditors with liens on sold assets typically see their liens attach to proceeds instead of the physical property, preserving their position without blocking the sale itself.
The bankruptcy case itself does not end at closing. If it is a liquidating Chapter 11, sale proceeds usually fund a plan of liquidation or wind-down trust distributing cash to creditors in priority order. If reorganization remains viable, proceeds might instead pay down secured debt or fund operations of a smaller, restructured entity emerging from the case. Either way, the sale order becomes a defining event in the case’s remaining trajectory, and objections to distribution priority often surface only after the sale itself is behind the parties.
How Does a 363 Sale Compare to a Plan Sale or a Private Sale?
A Section 363 sale is not the only path to move distressed assets, and the choice between methods depends heavily on timeline pressure and the debtor’s negotiating leverage.
A sale under a confirmed Chapter 11 plan folds the asset transfer into the broader reorganization, requiring creditor voting and a confirmation hearing. That process takes considerably longer than a standalone 363 sale and works best when the debtor has time to negotiate a consensual plan with major creditor constituencies. A 363 sale, by contrast, can close before a plan is ever proposed, which matters enormously when carrying costs or a melting ice cube of enterprise value make delay the enemy.
Selling assets entirely outside bankruptcy avoids court involvement altogether, but it sacrifices the two features that make 363 sales attractive: the free-and-clear transfer under §363(f) and the good-faith purchaser protection under §363(m). A buyer purchasing from a distressed but non-bankrupt seller inherits far more successor-liability risk and typically demands a lower price or extensive indemnities to compensate.
For sellers facing genuine urgency, a plant closure with mounting utility and security costs, a lender calling a default, a government agency needing to dispose of forfeited assets, the 363 process offers the fastest route to a court-blessed, clean-title transaction. Plan sales suit debtors with more runway and a cooperative creditor base. Private sales suit healthy companies divesting non-core assets outside financial distress, where successor liability risk is lower to begin with.
What Objections Commonly Arise During a 363 Sale?
Creditors, competing bidders, and sometimes the U.S. Trustee raise predictable objections, and understanding them in advance lets sellers structure a sale that survives scrutiny.
The most frequent objection challenges whether bid procedures unfairly favor the stalking horse bidder. Creditors’ committees scrutinize break-up fees, expense reimbursement caps, and minimum overbid increments, arguing that overly generous stalking horse protections chill competitive bidding. Courts generally uphold protections that are proportionate and were negotiated at arm’s length, but they will modify or reject terms that appear designed to entrench a single buyer.
A second common objection concerns adequate protection for secured creditors, particularly when sale proceeds may not cover the full secured debt. Lenders often negotiate lien attachment to proceeds or a carve-out for professional fees before withdrawing an objection.
Contract counterparties frequently object to cure amounts calculated for assumed executory contracts, arguing the debtor understated what is owed before assignment. These disputes usually resolve through negotiation or a separate cure hearing rather than derailing the sale itself.
Finally, some objections challenge the sale timeline as too compressed for meaningful marketing, arguing bidders lacked adequate diligence time. Debtors counter this by showing carrying costs, an established marketing record predating the motion, and expert testimony that further delay would destroy value. Courts weigh these factors under the same business-judgment standard that governs the initial decision to sell.
What Kinds of Assets Get Sold Through Section 363?
Section 363 sales handle an unusually broad range of asset types, which is part of why the process has become the default liquidation tool for distressed U.S. companies across industries.
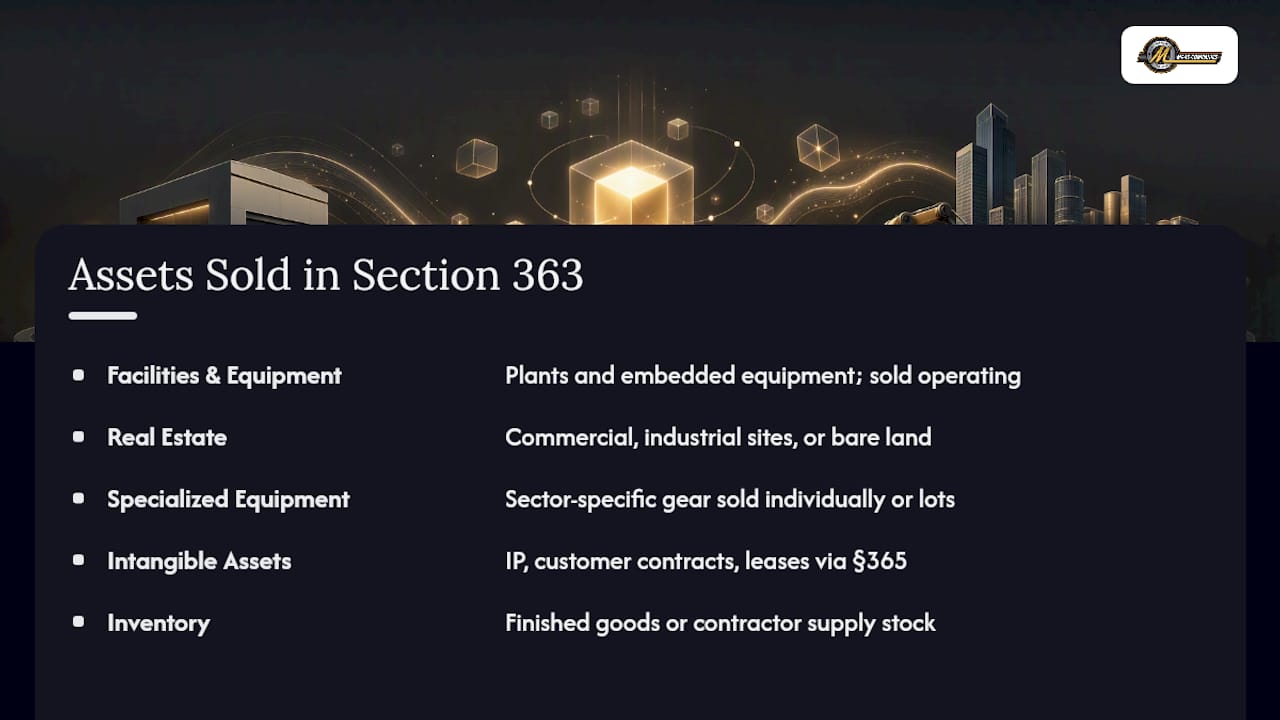
Manufacturing plants and their embedded equipment are among the most common candidates, often sold as a going concern when a buyer wants the facility operating rather than dismantled. Real estate, including commercial buildings, industrial sites, and even bare land, moves through the same process when a company’s core value sits in its property holdings. Specialized equipment across energy, hospitality, healthcare, education, and agricultural operations gets sold individually or in bulk lots depending on what generates the strongest aggregate return.
Intellectual property, customer contracts, and leases also transfer under §363 when paired with the §365 assumption-and-assignment process, giving buyers access to agreements a private sale might not let them keep. Inventory, whether finished goods or contractor supply stock, frequently sells through accelerated liquidation timelines tied to the same court-approved auction structure.
Not everything qualifies cleanly. Assets subject to unresolved title disputes, certain regulated licenses that require separate agency transfer approval, and property genuinely necessary for the debtor’s ongoing operations during the case face additional hurdles or exclusion from the sale pool entirely. Environmental liabilities tied to real property also warrant careful structuring, since some environmental obligations can survive a §363(f) transfer despite the free-and-clear language covering liens and claims.
Where the Conventional Advice on 363 Sales Falls Short
Most guidance on Section 363 sales treats the statute as the whole story: satisfy §363(f), get your good-faith finding, and the deal is done. That framing undersells the part that actually determines recovery, which is how aggressively the asset gets marketed before the bid deadline ever arrives.
The legal mechanics protect the transaction. They do nothing to guarantee a strong price. A stalking horse bid accepted without genuine competitive tension is a floor, not a ceiling, and too many sellers treat court approval as the finish line rather than the marketing campaign’s deadline.
What the evidence here actually supports is a sequencing discipline: start buyer outreach before the bid procedures motion is filed, not after it is approved. Debtors who wait for court blessing before picking up the phone lose two or three weeks of the very runway that produces competing bids. The reader’s first priority should not be the statute. It should be whether the marketing plan is aggressive enough to make the auction real rather than ceremonial.
— Vector
Working With Maas Companies on a Court-Supervised Sale
Maas Companies is the strategic partner that turns a court’s bid procedures order into a genuinely competitive auction, not just a compliant one. Where many advisors stop at filing the motion and waiting for bidders to appear, Maas builds targeted buyer outreach into the marketing plan from day one, drawing on decades of experience selling industrial plants, equipment, and commercial property across manufacturing, energy, agriculture, and contractor sectors.
Engaging Maas means court-savvy sale planning paired with aggressive, industry-specific advertising designed to bring qualified bidders to the table before the deadline, not after. The team coordinates with debtor counsel and investment bankers to keep the marketing timeline aligned with court deadlines, and structures outreach around the buyer networks most likely to bid competitively for a given asset class. For corporate executives, lenders, or counsel evaluating whether a court-supervised sale fits a distressed situation, the Maas Companies services for sellers page outlines how engagements typically begin and what recovery-focused planning looks like from the first conversation.
Primary Sources for Section 363 Sale Guidance
- 11 U.S. Code § 363 for the statutory text
- Mayer Brown’s practice note on sale considerations
- Goodwin’s primer on bankruptcy sale questions
- Acquisition Stars’ timeline breakdown of process and procedures
Sources
- Section 363 Sales Considerations | Insights | Mayer Brown
- 11 U.S. Code § 363 - Use, sale, or lease of property
- Top 10 Questions About Bankruptcy Sales – A Primer on Sales Under Section 363 of the Bankruptcy Code | Goodwin
- Section 363 Sale Process: Timeline and Procedures | Acquisition Stars
Recommended
- Bankruptcy Asset Sale Procedures: A 2026 Guide | Blog | Insights on Asset Liquidation and Auction Trends
- Bankruptcy Asset Management Tips for Creditors: Maximize Recovery | Blog | Insights on Asset Liquidation and Auction Trends
- Liquidation sales explained: Maximize asset recovery | Blog | Insights on Asset Liquidation and Auction Trends
- Definition of Bulk Asset Sales for Executives | Blog | Insights on Asset Liquidation and Auction Trends