Blog
Solar Equipment Liquidation: An Executive Recovery Playbook

Solar equipment liquidation delivers the highest capital recovery when it runs as a managed orderly negotiated sale, not a distressed dump onto secondary markets. For an institutional owner, lender, or public agency holding a decommissioned or surplus solar plant, the single most important move right now is commissioning an urgent valuation and marketability audit before the sale window narrows.
That audit typically draws on PPA and REC contract reviews, an assessment of outstanding decommissioning bonds, and benchmarking against recognized frameworks such as EPRI’s decommissioning guidance. A qualified liquidation partner should deliver, within the first 7 to 14 days:
- A full scope audit covering modules, inverters, racking, BESS components, and spare parts inventory
- A legal and regulatory checklist flagging permit, interconnection, and hazardous-waste obligations
- A marketability memo estimating realistic recovery ranges and buyer demand
The board-level verdict is straightforward: if PPA status is intact and no covenant breach has been declared, proceed to a scoped engagement immediately. If the asset is already in receivership, recovery options narrow fast. Maas Companies Inc. is one firm that structures this kind of engagement for corporate, lender, and government clients.
Key Takeaways
Professional, structured liquidation recovers more capital than distressed or unmanaged disposal because it preserves contract value, controls compliance risk, and reaches pre-qualified institutional buyers.
| Point | Details |
|---|---|
| Act before default | Structured pre-default sales recover materially more than unmanaged receiverships, per industry transaction data. |
| Audit contracts first | PPA and REC status often drive more recovery variance than equipment age or specifications. |
| Budget for compliance | Decommissioning bonds, hazardous-waste testing, and site restoration costs must be modeled before marketing begins. |
| Use institutional channels | Pre-qualified buyer networks close faster and at higher prices than open consumer marketplaces. |
| Vet your partner | Maas Companies structures orderly negotiated sales with documented escrow and settlement procedures for lenders and corporate owners. |
Table of Contents
- When Do Institutional Clients Need Professional Solar Asset Liquidation?
- What Does a Professional Liquidation Engagement Cover?
- What Recovery Range Should You Expect, and What Drives It?
- How Does the Liquidation Process Work From Start to Finish?
- How Do You Select the Right Liquidation Partner?
- What Track Record Should You Expect From a Liquidation Partner?
- Why Most Owners Underestimate the Cost of Waiting
- How Maas Companies Supports Institutional Solar Asset Recovery
- Sources
When Do Institutional Clients Need Professional Solar Asset Liquidation?
The decision to liquidate rarely comes from a single event. It comes from a convergence of financial and operational signals that tell an asset manager the current ownership structure no longer makes sense. Recognizing the trigger early is what separates a strong recovery from a fire sale.
Common triggers include:
- Plant closure or planned decommissioning at end of useful life
- Lender covenant breach, pre-notice of default, or foreclosure proceedings
- Material excess inventory from canceled projects or overordering
- Impending PPA or REC delivery shortfalls that threaten contract penalties
- Deteriorating host or offtaker credit quality
- Planned corporate restructuring, divestiture, or repowering of an existing site
Timing determines the outcome more than almost any other variable. Structured pre-default sales and orderly negotiated sales consistently recover materially more value than assets that fall into unmanaged receivership, and that gap tends to widen the longer a distressed owner waits. Asset managers and CFOs should treat the 60 to 90 day period after a covenant breach notice or restructuring decision as the active window for a structured sale. Watch debt service coverage ratio trends, PPA compliance status, and SREC or REC delivery performance. Once any of those slip into default territory, buyer leverage increases and pricing power shifts away from the seller.
What Does a Professional Liquidation Engagement Cover?
A solar liquidation engagement is broader than moving hardware off a balance sheet. It spans physical assets, contractual obligations, and regulatory compliance simultaneously, and treating any one of those in isolation is where recoveries get eroded.
The asset scope typically includes:
- PV modules and racking or mounting systems
- Inverters, transformers, and switchgear
- Cabling, foundations, and balance-of-system components
- Battery energy storage system (BESS) hardware
- Spare parts and O&M inventory
Regulatory and legal obligations run alongside the physical inventory. Counsel should verify permit status, confirm whether hazardous-waste classification or RCRA/TCLP testing applies to any BESS or panel components, and clarify who is responsible for utility interconnection transfer. PPA assignment or termination clauses need review before marketing begins, since a mishandled contract transfer can void the value a buyer is paying for. Local demolition and transport permits also factor into the timeline.
Financial assurance is where many owners underestimate their exposure. Decommissioning bonds, escrow arrangements, and letters of credit are common structures, and many decommissioning plans remain high-level, leaving the asset owner or lender on the hook for removal and restoration costs unless a financial assurance mechanism is already in place. Buyers will also expect documentation: chain-of-custody records and recycler certifications such as R2 or ISO standards are increasingly a condition of sale, not a nice-to-have.
What Recovery Range Should You Expect, and What Drives It?
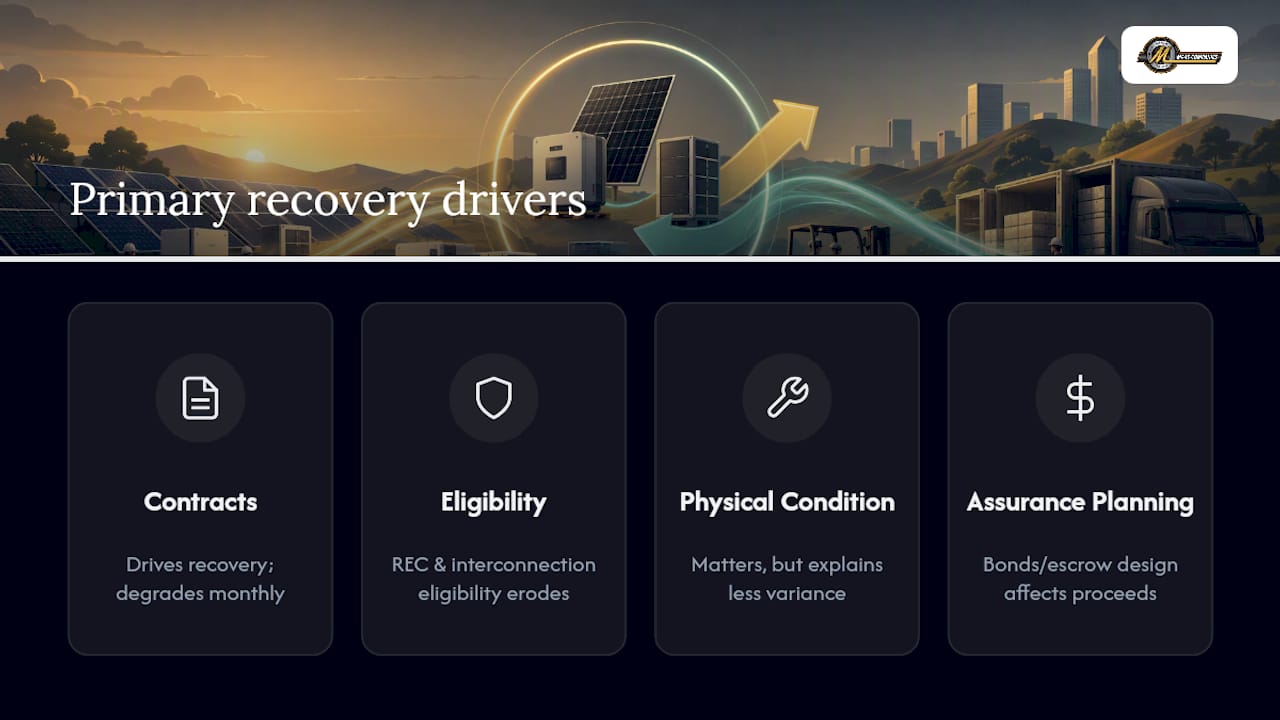
Recovery outcomes vary widely, and the single biggest lever is whether the sale is structured before default or forced after it. Structured, pre-default sales recover materially more than unmanaged receiverships, with the gap driven largely by debt type, PPA status, and REC or SREC eligibility rather than by the physical condition of the equipment itself.
Recovery insight: according to industry analysis of distressed commercial solar transactions, state-level program eligibility and contract status explain more recovery variance across portfolios than module age or output specifications alone.
Valuation hinges on several interlocking factors:
- Module efficiency and remaining useful life relative to current market specifications
- Secondary-market demand for the specific inverter and racking configuration
- Whether PPA or SREC contracts remain assignable to a buyer
- Interconnection queue position and grid connection status
- State program eligibility for incentives tied to the site
- Removal, transport, and recycling logistics costs
Timelines generally run from initial assessment through marketing, sale execution, and settlement over a period of several months, though improved dismantling techniques are beginning to compress that schedule in some engagements. The cost drivers that erode net recoverable value most are removal and transport expenses, recycling or disposal fees, potential Investment Tax Credit recapture exposure, and legal costs tied to contract assignment. Residual value should always be modeled net of these costs, not as a headline salvage figure, since overstating recoverable value is one of the most common underwriting failures in distressed energy asset sales.
How Does the Liquidation Process Work From Start to Finish?
A disciplined liquidation partner follows a sequence designed to protect contract value while moving quickly enough to preserve buyer interest. Skipping steps to save time almost always costs more in final recovery than it saves in schedule.
- Intake and rapid valuation (weeks 0 to 2). The partner audits the asset register, confirms ownership documentation, and produces a preliminary marketability memo.
- Legal and PPA/REC audit. Counsel reviews contract assignability, interconnection agreements, and any pending compliance issues.
- Decommissioning and environmental scope. The team confirms hazardous-waste classification, bond status, and site restoration obligations.
- Removal and logistics planning. Transport, staging, and recycling pathways get mapped against buyer requirements.
- Marketing to pre-qualified buyers. Institutional and secondary-market channels are activated rather than open consumer listings.
- Sale execution. An orderly negotiated sale or specialized auction runs against a defined bid deadline.
- Settlement and escrow. Funds clear through documented escrow instructions with performance guarantees in place.
- Asset removal and site remediation. Physical decommissioning proceeds under the agreed timeline and compliance checklist.
Deliverables at each stage should include a letter of intent template, formal marketing materials, a buyer pre-qualification list, escrow instructions, and a final settlement report. Lenders and counsel should insist on defined control points: verified escrow mechanics, buyer performance guarantees, and certificated asset transfers before any funds release.
Pro Tip: Marketing to pre-qualified institutional buyers and specialized secondary-market channels, rather than open consumer platforms, is what preserves the value of intact PPA and REC contract streams. Pre-qualified buyer networks close faster and at higher prices because transaction risk is lower on both sides.
How Do You Select the Right Liquidation Partner?
Choosing a liquidation partner is a due-diligence exercise, not a procurement formality. The wrong choice can leave contract value on the table or expose the seller to compliance risk that surfaces months after closing.
Look for a partner with demonstrated capability across these areas:
- Technical solar asset marketing experience, not general equipment auction background alone
- REC and PPA legal review experience specific to renewable energy contracts
- An established recycler and BESS-handling network with documented certifications
- Proven escrow and settlement procedures with a track record among lenders
- Insurer-approved workflows and documented liability coverage
Ask prospective partners for transaction references, recent recovery benchmarks on comparable assets, and a description of their institutional buyer network. Get specifics on fee structure (success fee versus retainer), escrow mechanics, insurance coverages, and whether they will commit to a timeline.
A partner that cannot produce a documented institutional buyer list, or that describes settlement mechanics only in vague terms, is not equipped to protect a lender’s or a government agency’s recovery position. Fee transparency and escrow discipline are non-negotiable at this scale.
The engagement letter itself should spell out scope, a fee cap or performance-fee structure, escrow instructions, ownership of marketing materials, confidentiality terms, buyer pre-qualification standards, and how any outstanding bond is handled at close. Red flags include reliance on consumer marketplaces instead of institutional channels, no prior experience with REC or PPA assignment, and fee disclosures that shift after the engagement starts. Maas Companies has structured orderly negotiated sales for lenders and corporate owners across multiple asset classes, which is the kind of track record worth requesting in writing before signing anything.
What Track Record Should You Expect From a Liquidation Partner?
Institutional sellers should ask for comparable experience, not just solar-specific case studies, since the underlying skills (buyer vetting, escrow discipline, contract-sensitive marketing) transfer directly across asset classes.
Representative engagement types include:
- An orderly negotiated sale of surplus biodiesel processing equipment with a 6,000 gallon per day capacity, run for an institutional seller needing coordinated buyer outreach
- Marketing and sale of large industrial switchgear requiring specialized technical buyer identification
- Lender-directed sales of surplus industrial energy equipment where escrow and settlement transparency were central to closing
What this signals for solar specifically: the same institutional marketing discipline, buyer vetting rigor, and escrow handling apply directly to BESS components and REC-linked contract transfers, where a mishandled buyer relationship or an opaque settlement process can quietly erase recovery. Exact dollar outcomes on individual engagements are often confidential to the client, but the operational pattern (pre-qualified outreach, documented settlement, transparent reporting) is consistent across asset types.
Why Most Owners Underestimate the Cost of Waiting
The conventional advice on solar asset liquidation treats it as a hardware disposal problem: find a buyer, move the panels, close the file. That framing consistently undersells what actually drives recovery. The real value sits in the contracts wrapped around the hardware, the PPA, the REC eligibility, the interconnection position, and those degrade every month a distressed owner delays engaging a specialist.
What gets overrated is the physical condition of the equipment itself. Module efficiency matters, but it explains far less recovery variance than contract status and state program eligibility. What gets underrated is financial assurance planning. Owners who treat decommissioning bonds and escrow structure as paperwork to handle at closing, rather than as design decisions made at the start of the engagement, routinely leave money on the table or inherit remediation liability they did not anticipate.
The priority for any executive reading this: get the marketability audit done before a covenant breach or restructuring decision becomes public. Waiting for certainty is what turns a structured sale into a distressed one.
How Maas Companies Supports Institutional Solar Asset Recovery
Maas Companies works with lenders, corporate owners, and government agencies to structure orderly negotiated sales and specialized auctions for decommissioned or surplus solar assets, treating recovery as a marketing and legal discipline rather than a liquidation of last resort.
The engagement model includes buyer pre-qualification, escrow-backed settlement procedures, and coordination around outstanding decommissioning bonds so that financial assurance obligations are addressed before closing, not after. Settlement reporting is documented and transparent, which matters to lenders and counsel who need a defensible record for their own stakeholders. If your organization is holding a decommissioned plant, an excess inventory position, or an asset heading toward restructuring, the practical next step is requesting a scoped valuation and marketability audit through Maas Companies’ team, or reviewing the full range of institutional liquidation services before deciding how to proceed.
Sources
- What Happens to a Commercial Solar Project When It Distress
- Solar and Battery End-of-Life Considerations (CT Green Bank)
- PV hardware resale: turning excess inventory into opportunity (EnergyBin)
- Decommissioning risk & residual value in energy assets (Buckstop)
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Recommended
- Equipment liquidation explained: maximizing asset recovery | Blog | Insights on Asset Liquidation and Auction Trends
- Equipment Liquidation Workflow: Maximize Asset Recovery | Blog | Insights on Asset Liquidation and Auction Trends
- How Industrial Plant Liquidation Maximizes Recovery Value for Lenders | Blog | Insights on Asset Liquidation and Auction Trends
- Plant liquidation strategies: maximize recovery in 2026 | Blog | Insights on Asset Liquidation and Auction Trends