Blog
The UCC Termination Statement Process: What Filers Must Know

A UCC-3 termination statement cancels the public notice a secured party filed against a debtor’s collateral, and it typically falls to that secured party to file it. Once the underlying debt is satisfied, UCC § 9-513 sets the clock: one month for consumer goods, or 20 days after a debtor’s authenticated demand. If the deadline passes without action, confirm your original filing number and filing office, then send that demand in writing.
TL;DR:
- Filing a UCC-3 termination must be done within one month of satisfaction for consumer goods or 20 days after an authenticated debtor demand for commercial collateral.
- Accurate matching of the original filing number and debtor name is crucial to prevent rejection or misindexing of the termination statement.
- The secured party or debtor, if the secured party fails to respond timely, can authorize or file the termination directly, but proper proof of delivery and documentation are essential.
- Coordinating UCC terminations early in asset disposition plans helps prevent delays, reduces closing times, and protects the overall recovery value.
- Checking the filing status through the state’s database and ordering certified copies or UCC-11 reports ensures reliable proof of lien releases before asset sale.
Table of Contents
- Understanding the UCC Termination Statement Process and Its Purpose
- Who Can Authorize a UCC Termination Filing?
- How to Prepare and File a UCC-3 Termination Statement
- What Are the Statutory Deadlines for Filing a Termination?
- Common Mistakes That Delay or Invalidate a Termination
- How to Verify a Termination Filed and Get Proof for Closing
- Best Practices for Lien Cleanup Before an Asset Sale
- Why Prompt Lien Cleanup Protects Recovery Value
- How Maas Companies Supports Lien Cleanup and Sale-Ready Disposition
- Sources
Understanding the UCC Termination Statement Process and Its Purpose
A UCC-3 termination formally ends the legal effectiveness of a UCC-1 financing statement. It tells the world, through the state’s public record, that the secured party no longer claims an interest in the collateral described in the original filing. That distinction sets it apart from other UCC-3 amendment types: a partial release removes only some collateral or debtors while leaving the lien intact for the rest. A collateral change modifies what’s covered without ending the filing, and a continuation extends the lien’s life instead of closing it out.
Filers reach for a termination in a few recurring situations. A loan gets paid off in full. A lender sells the underlying receivable and the buyer’s new financing statement supersedes the old one. Or a UCC-1 was filed against the wrong debtor entirely, and someone needs to correct the public record. Each scenario ends the same way: a properly filed UCC-3 with the termination box checked, matched exactly to the original filing number.
Who Can Authorize a UCC Termination Filing?
Authorization runs through the secured party by default, and UCC § 9-513 spells out exactly when that party must act. For consumer goods, filing a termination shortly after satisfaction is an affirmative duty, not a courtesy; for commercial collateral, the secured party has no automatic filing obligation until the debtor sends an authenticated demand, at which point a 20-day response window opens.
An authenticated demand is a signed, dated written request from the debtor stating the obligation has been satisfied and asking the secured party to terminate. Send it to the address listed on the original financing statement, and keep proof of delivery, certified mail or a tracked courier service works well here. If the secured party still doesn’t respond within that window, the debtor gains the right to file the termination directly, provided the filing states the authorization basis and confirms the debt is satisfied.
How to Prepare and File a UCC-3 Termination Statement
Filing correctly the first time saves weeks of rework. Follow this sequence:
- Pull the original UCC-1. Search the state Secretary of State’s UCC database by debtor name or filing number to confirm the financing statement is still active, not already lapsed or terminated.
- Identify the correct filing office. UCC filings are almost always made in the debtor’s state of organization for registered entities, so file the UCC-3 there, not wherever the collateral physically sits.
- Complete the UCC-3 form accurately. Check the termination box specifically. Selecting “continuation” or “collateral change” instead will not release the lien and is one of the most common technical errors filers make. Enter the authorizing party’s name exactly as it appears on the original UCC-1, and match the initial filing number character for character.
- Submit through the state’s accepted method. Most Secretary of State offices, including Iowa’s and New York’s, now run online filing portals alongside mail and in-person options. Debtor-filed terminations sometimes require an attached sworn statement confirming the authenticated demand and the secured party’s inaction.
- Keep records. Save the filing receipt and request a certified copy of the terminated statement. For higher-stakes transactions, order a formal UCC-11 search report, which gives lenders and title companies a documented, third-party-verifiable snapshot of the filing’s status.
Pro Tip: File the termination before you list collateral for sale, not after a buyer’s diligence team flags it. A stale lien discovered mid-negotiation stalls closings far longer than the filing itself ever takes.
What Are the Statutory Deadlines for Filing a Termination?
The timing rules under UCC § 9-513 are specific and unforgiving. For consumer goods, the secured party must file within one month of satisfaction or within 20 days of an authenticated demand, whichever comes first. For non-consumer collateral, there’s no automatic duty. The obligation triggers only after the debtor sends that authenticated demand, starting a 20-day clock.
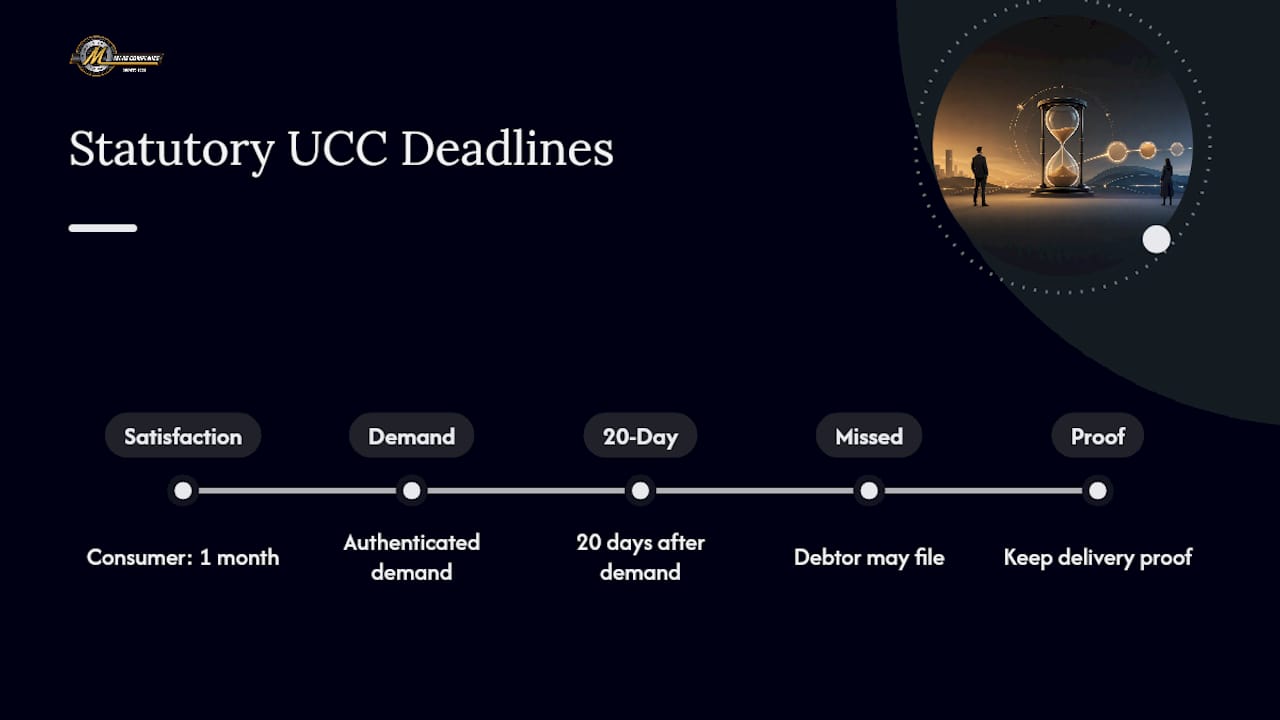
Miss that window and the debtor is authorized to file the termination directly. Document everything: the demand letter, its delivery method, and the date sent. Certified mail with a return receipt or a courier delivery confirmation gives you defensible proof if the filing’s validity is ever challenged later, particularly in a refinancing or sale where a lender’s counsel will ask for it.
Common Mistakes That Delay or Invalidate a Termination
Most rejected or ineffective UCC-3 terminations trace back to a handful of recurring errors.
- Name mismatches. Even a minor variation in the debtor or secured party’s legal name between the original UCC-1 and the UCC-3 can cause rejection or misindexing.
- Filing number errors. The termination must reference the exact initial filing number; a single transposed digit sends the filing nowhere useful.
- Wrong checkbox. Selecting continuation or collateral change instead of termination leaves the lien fully intact.
- Multiple secured parties. If more than one secured party is listed on the original filing and only one authorizes the termination, the lien stays active for the others. Coordinate separate terminations or a joint release.
- Wrong address for demands. Authenticated demands sent anywhere other than the address on the original financing statement can be challenged as improperly delivered.
How to Verify a Termination Filed and Get Proof for Closing
Run a fresh UCC search through the state Secretary of State’s database, filtering by debtor name or the original filing number, to confirm the termination shows as recorded. For deals where certainty matters, most closings, refinancings, and lender underwriting qualify, order a certified copy of the filed UCC-3 or a formal UCC-11 information report, which gives counsel and underwriters a document they can rely on without re-verifying it themselves.
If the termination doesn’t appear within the state’s normal processing window, contact the filing office directly before assuming something is wrong. Processing backlogs happen. If the office confirms a filing defect, correct and resubmit rather than waiting; a second attempt with accurate names and filing numbers usually clears within days.
Best Practices for Lien Cleanup Before an Asset Sale
Teams managing industrial asset dispositions get the best outcomes when commercial equipment identification plates and UCC termination checks are built into the liquidation schedule from day one, not handled as a last-minute fix before closing. Pull UCC searches on every piece of collateral early enough to send authenticated demands and clear the 20-day statutory window before a buyer’s escrow agent or title reviewer even asks.
Coordinate timing tightly: a termination filed the week before closing does little good if the buyer’s lender needs five business days to review a certified UCC-11 report. Build that lead time into the sale calendar.
Pro Tip: Keep a standing file, per asset or per transaction, containing the demand letter, proof of delivery, the filed UCC-3, and a certified copy or UCC-11 report. That paper trail becomes the first thing indemnity negotiations reference if a buyer later questions clear title.
Why Prompt Lien Cleanup Protects Recovery Value
Stale liens are quiet deal killers. Buyers hesitate, lenders stall financing, and closings slip by weeks while someone tracks down a filing number from a loan paid off years ago. Asset recovery teams that treat UCC termination as a scheduling item, not an afterthought, consistently shorten sales cycles and protect the net proceeds a sale was supposed to deliver in the first place.
— Vector
How Maas Companies Supports Lien Cleanup and Sale-Ready Disposition
Coordinating UCC terminations across dozens of collateral items, multiple secured parties, and tight closing timelines is exactly the kind of operational friction that stalls industrial asset sales. Maas Companies works alongside lenders, corporate sellers, and government agencies to verify lien status, retrieve certified proof, and sequence sale execution so title issues get resolved before they can delay a closing rather than during one.
That coordination matters most during plant closures, restructuring, and lender-directed liquidations, situations where dozens of financing statements may need review against a compressed sale timeline. Maas Companies’ structured approach to liquidation planning folds lien verification directly into the auction and negotiated-sale schedule, alongside asset marketing and buyer coordination, so recovery isn’t held hostage by paperwork. For teams preparing an industrial plant, equipment portfolio, or commercial property for sale, Maas Companies offers a consultation to map out what needs clearing before the first buyer walks through the door.
Sources
- § 9-513. TERMINATION STATEMENT. | Uniform Commercial Code | LII / Cornell Law
- UCC-3 Termination: What It Is and How to File - LegalClarity
- How do I file a UCC-3? - Iowa Secretary of State Help
Recommended
- Streamline Commercial Property Liquidation: Steps for Manufacturing Firms | Blog | Insights on Asset Liquidation and Auction Trends
- Facility Liquidation Strategies That Keep Transitions on Track | Blog | Insights on Asset Liquidation and Auction Trends
- Top Distressed Asset Liquidation Tools for Institutional Sellers | Blog | Insights on Asset Liquidation and Auction Trends
- Legal Professionals’ Checklist for Asset Recovery and Court-Ordered Sales | Blog | Insights on Asset Liquidation and Auction Trends